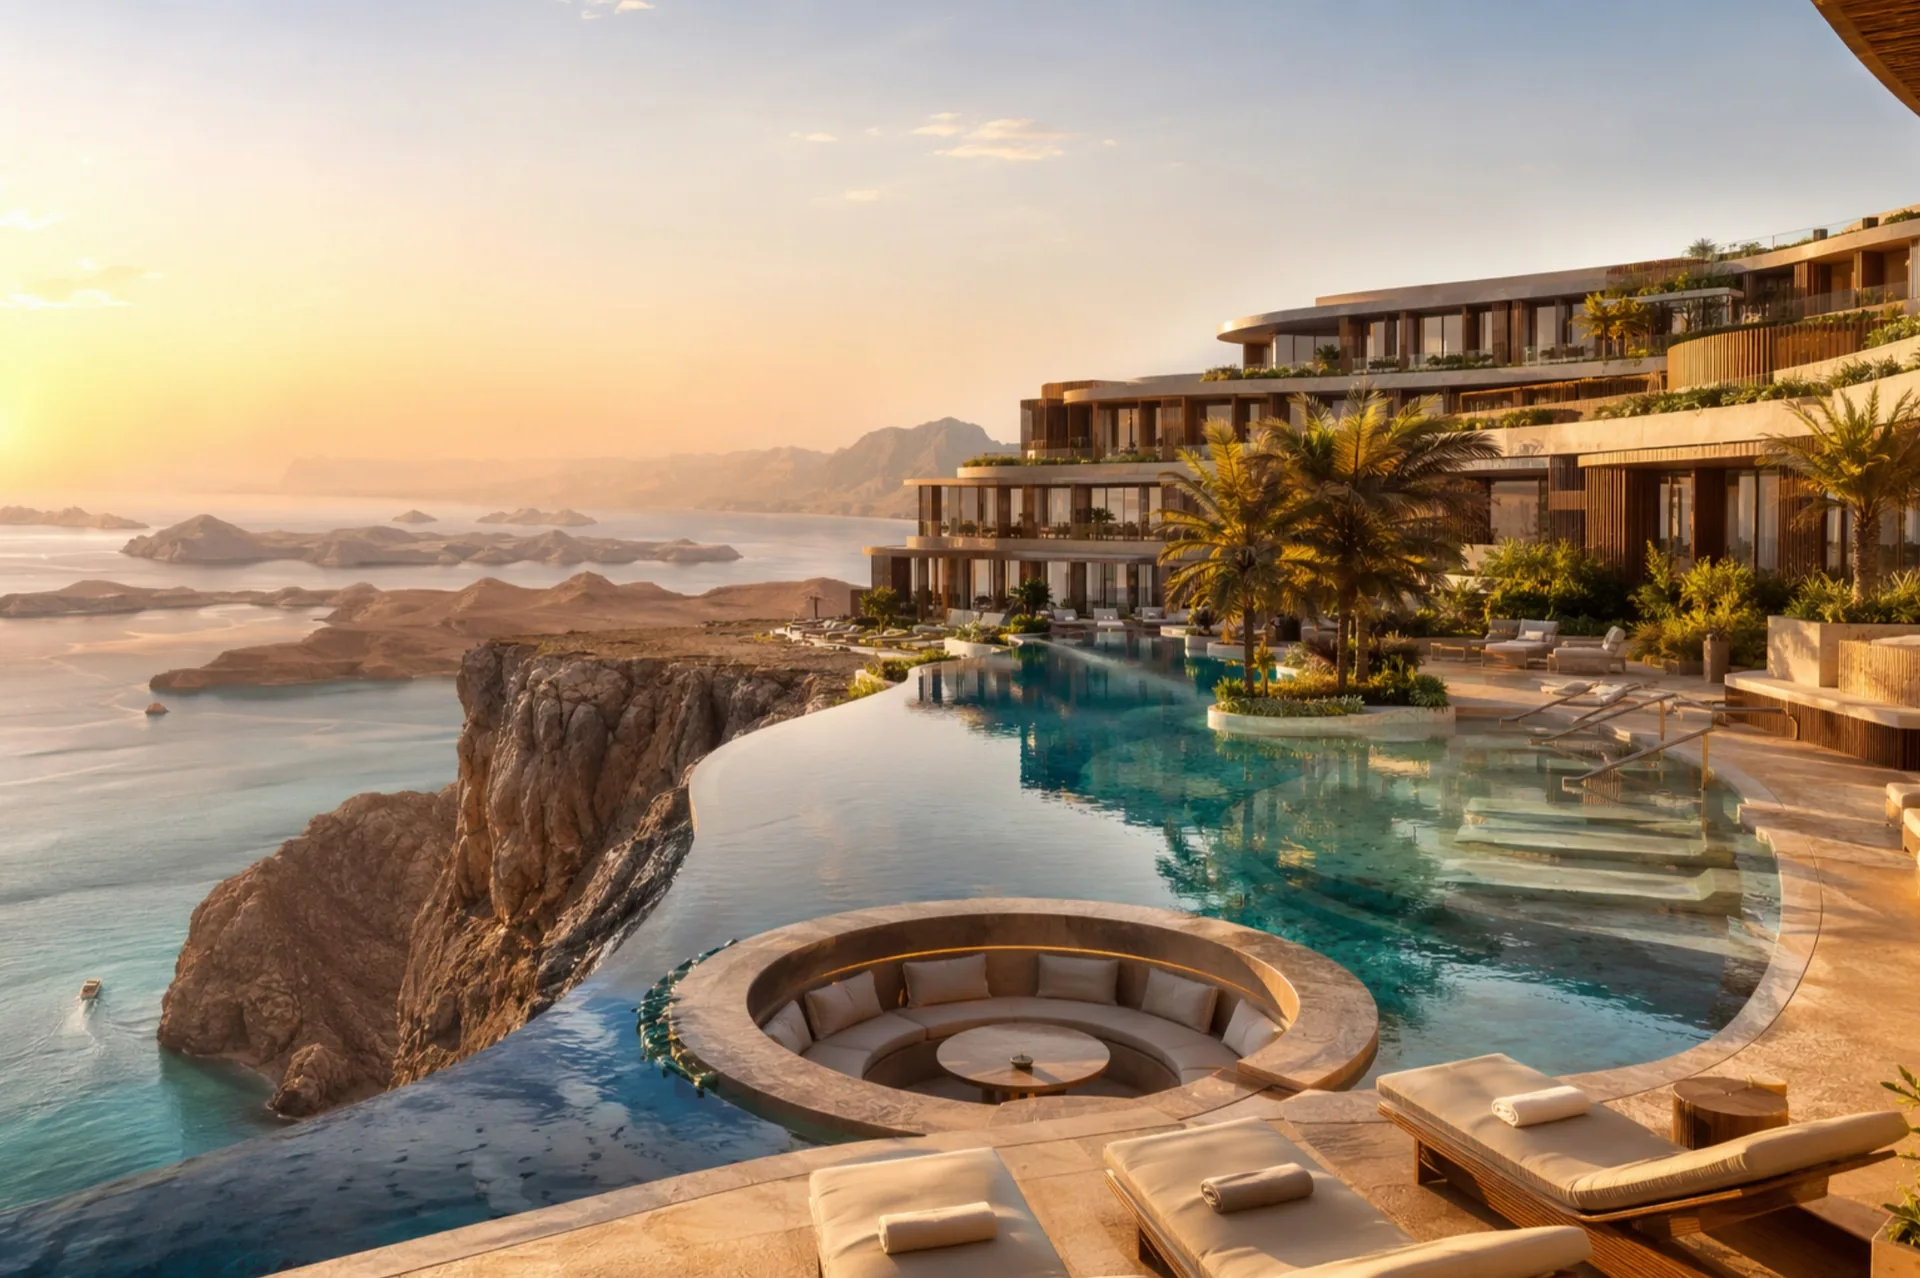
A boutique coastal resort and freehold residences on the highest summit of Bandar Al Khairan, 45 minutes from Muscat — a phased, documented development, open to investors.
One plan, three moves: reposition to the boutique standard the site commands, phase the capital keys-first, and monetise 79 freehold villas inside Oman's Integrated Tourism Complex regime.
AlKhyran Heights occupies a semi-flat plateau of 113,477 m² rising to 150 m — the highest point in the area — above the Bandar Al Khairan marine reserve, 35 km from central Muscat and 45 minutes from the international airport. The 2020 concept (3★, 199 keys, OMR 39.84 M committed in a single phase) did not capture this value: it returned a 0.2% IRR. This study rebuilds the project on 2025–2026 market data into an institutional-grade investment.
The plan: reposition to boutique 4★+/5★ — the route Anantara is taking one bay away (121 keys, OMR 36 M, opening 2027) — at a blended ADR of OMR 74.7 (~USD 194), in the lower third of Muscat luxury resort rates (USD 220–480). Phase the capital keys-first: phase 1 opens at OMR 16.4 M for 150 keys. Sell the 79 villas as freehold inside the ITC: +OMR 12.6 M collected 2030–2032, priced below market benchmarks and lifted by Oman's Golden Residency (10-year residency from OMR 200k invested in an ITC).
With the 2026 market correction (−11.7% revenue) already embedded in the ramp, the model delivers stabilised EBITDA of OMR 1.95 M on OMR 4.82 M revenue — an 11.9% yield on cost and an 11.3% project IRR (10.0% floor excluding exit premium). At 60/40 debt-equity: stabilised DSCR 2.37×, projected equity IRR of 15–17% (2026 model, including a year-10 exit), break-even at ~30% occupancy, and +40% to +59% value creation at stabilisation (exit cap 8.5–7.5%).
| The offer at a glance | |
|---|---|
| Phase-1 capital | 16.4 M OMR (≈ USD 42.6 M) |
| Equity ticket (40%) | 6.56 M OMR (≈ USD 17 M) |
| Unlevered project IRR | 11.3% (floor 10.0%) |
| Projected levered equity IRR | 15–17% (2026 model, projections — not guaranteed) |
| Value creation at stabilisation | +40% to +59% |
| Cumulative downside scenario | IRR ≈ 5–6%, DSCR ≈ 1.6× — capital preserved (§12) |
| Investor protections | Escrow, certified milestones, independent audit, veto rights (§11) |
Altitude is the asset's first quality: unobstructed sea views east and north from every parcel, where Muscat's shoreline is now saturated with beach-level developments.
The plateau sits between 140 and 150 m above the Bandar Al Khairan marine reserve. The nearest beach is under 500 m. The configuration is directly comparable to AIDA/Yiti (Dar Global + OMRAN) — a cliff plateau at 130 m, ~35 minutes from Muscat — which became in three years the sultanate's premium residential benchmark (villas OMR 385–808k, Trump Golf Villas ~USD 2.1 M, Cavendish Maxwell May 2025). Utilities are self-contained and already sized (desalination, sewage, four substations); the access road to build is only 300 m.
Bandar Al Khairan, ~30 km south-east of Muscat, is a marine reserve cited by Oman Vision 2040: 22+ dive sites, snorkelling, kayaking, mangrove and turtle grounds — a complete nature product under an hour from an airport serving 80+ destinations and 36 airlines. No branded resort is open there yet: the destination is on the eve of its go-to-market, with the first-mover advantage intact. A protected reserve caps competing supply permanently, and bay-front land scarcity supports rates for the long term.
Anantara Bandar Al Khairan — 121 keys, OMR 36 M, Musstir LLC (MB Holding) / Minor Hotels, opening 2027 — validates the location one bay away, creates the cluster effect (international signal, agency flows, access infrastructure) without closing the market: it leaves the family-boutique and residential niche open.
Muscat luxury resorts in operation trade at USD 220–480/night (The Chedi from OMR 150, Al Bustan ~USD 412 average, Al Husn to USD 624). The gap between the rate the site commands and the cost the concept commands is precisely the operation's margin.
Only a 300 m link road to build; desalination, sewage and four substations are integrated in the phase-1 capex (OMR 3.3 M) — the isolation premium HVS identifies for remote resorts is already priced in.
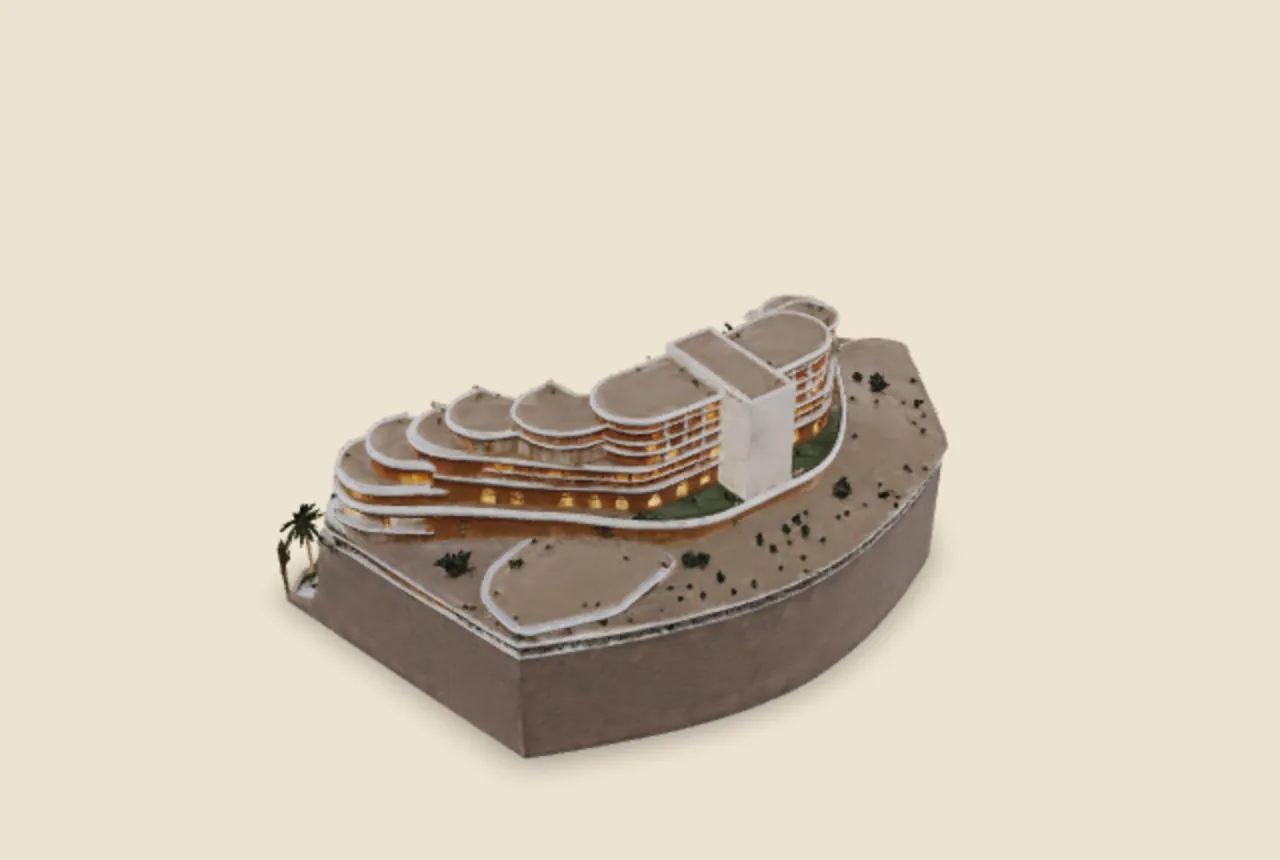
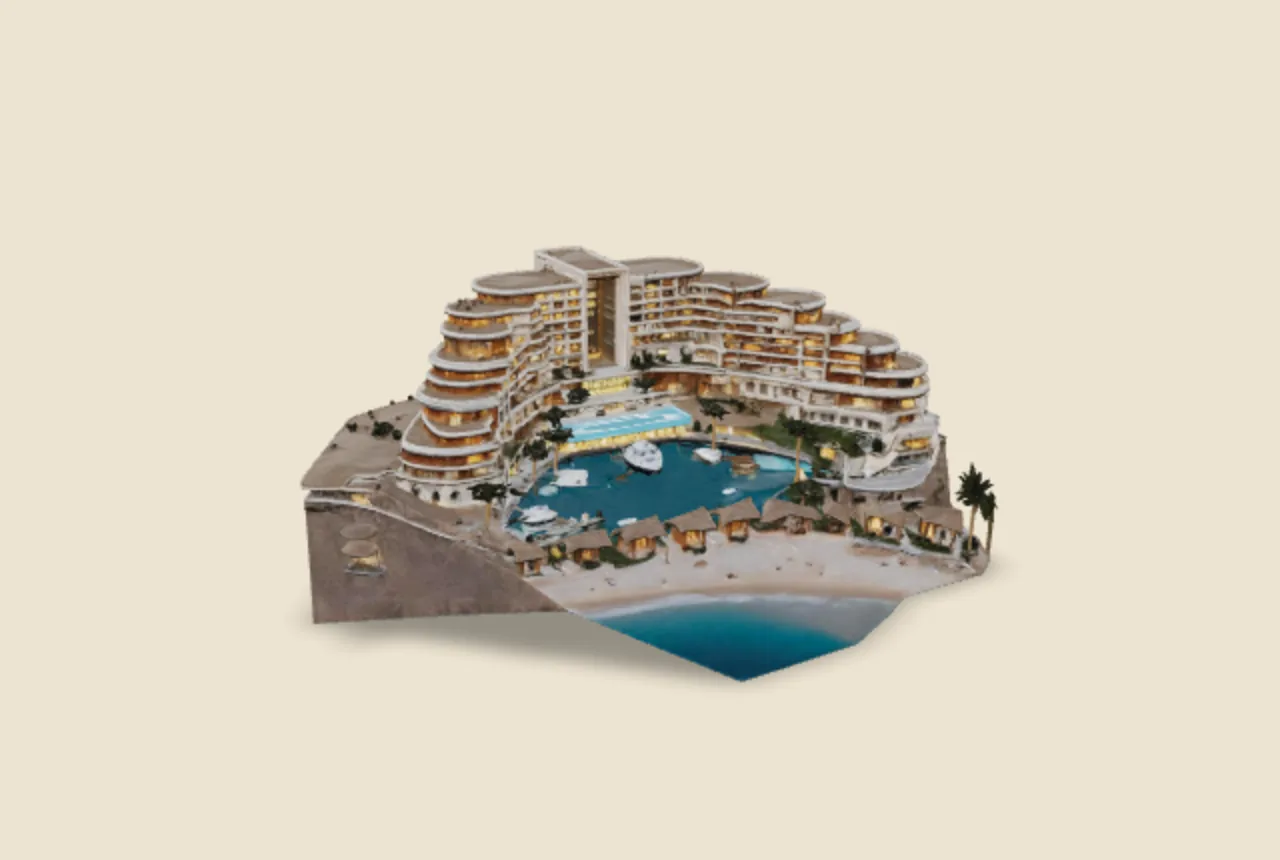
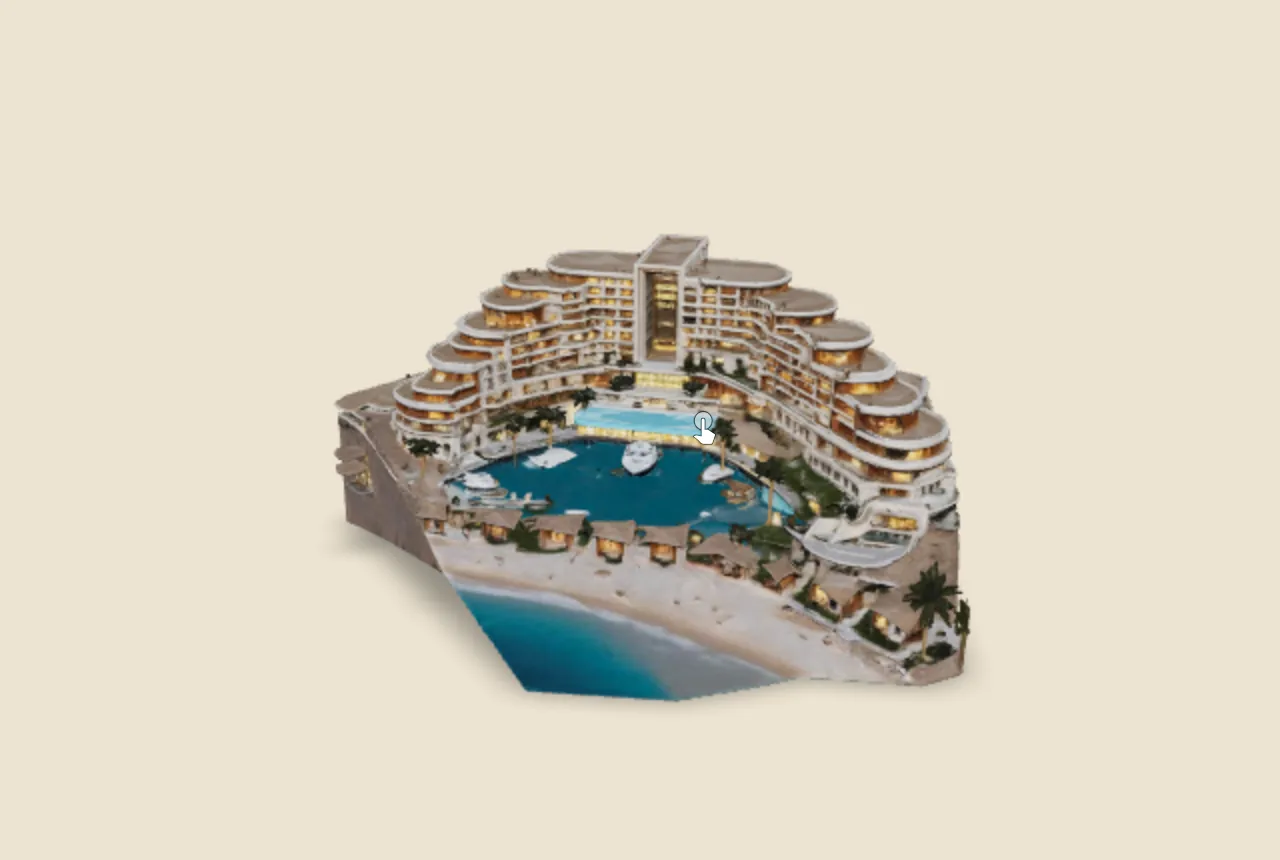
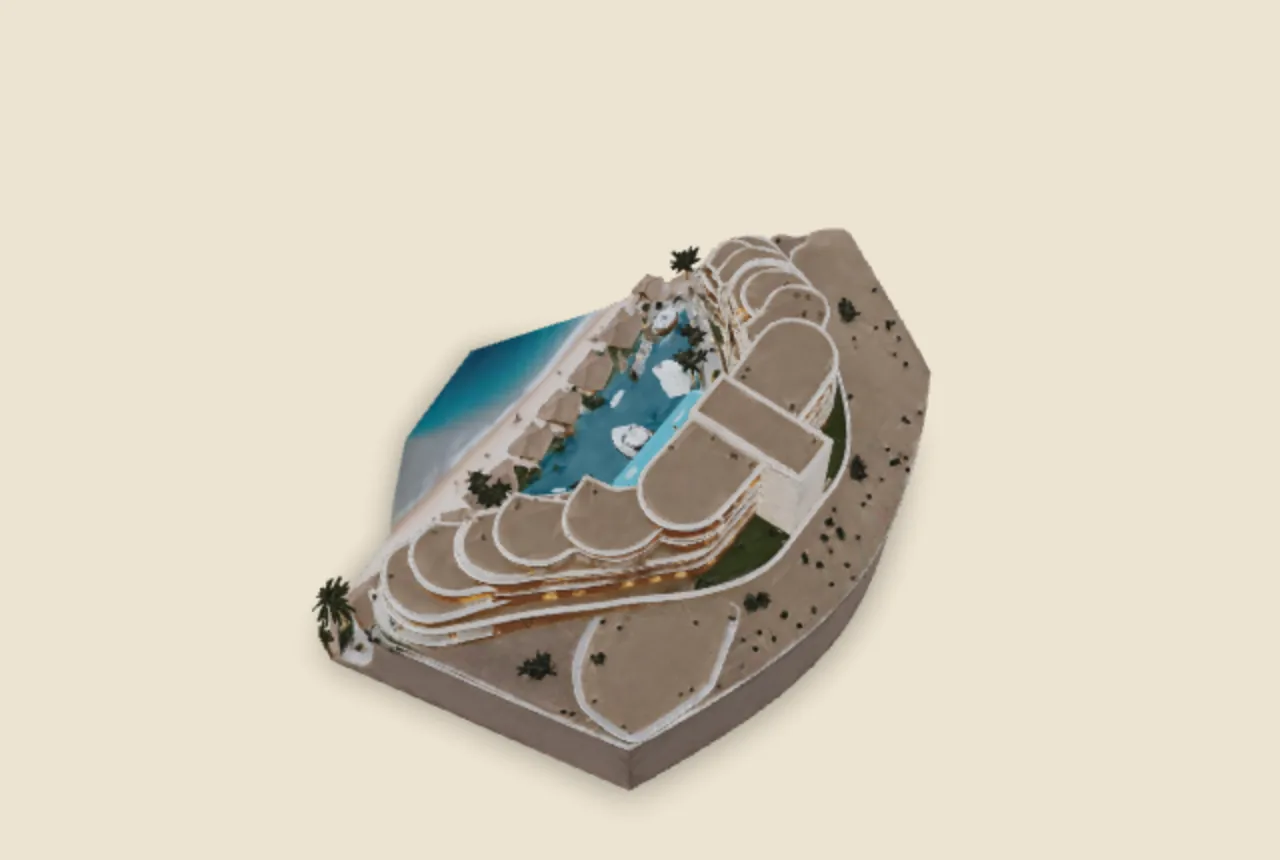
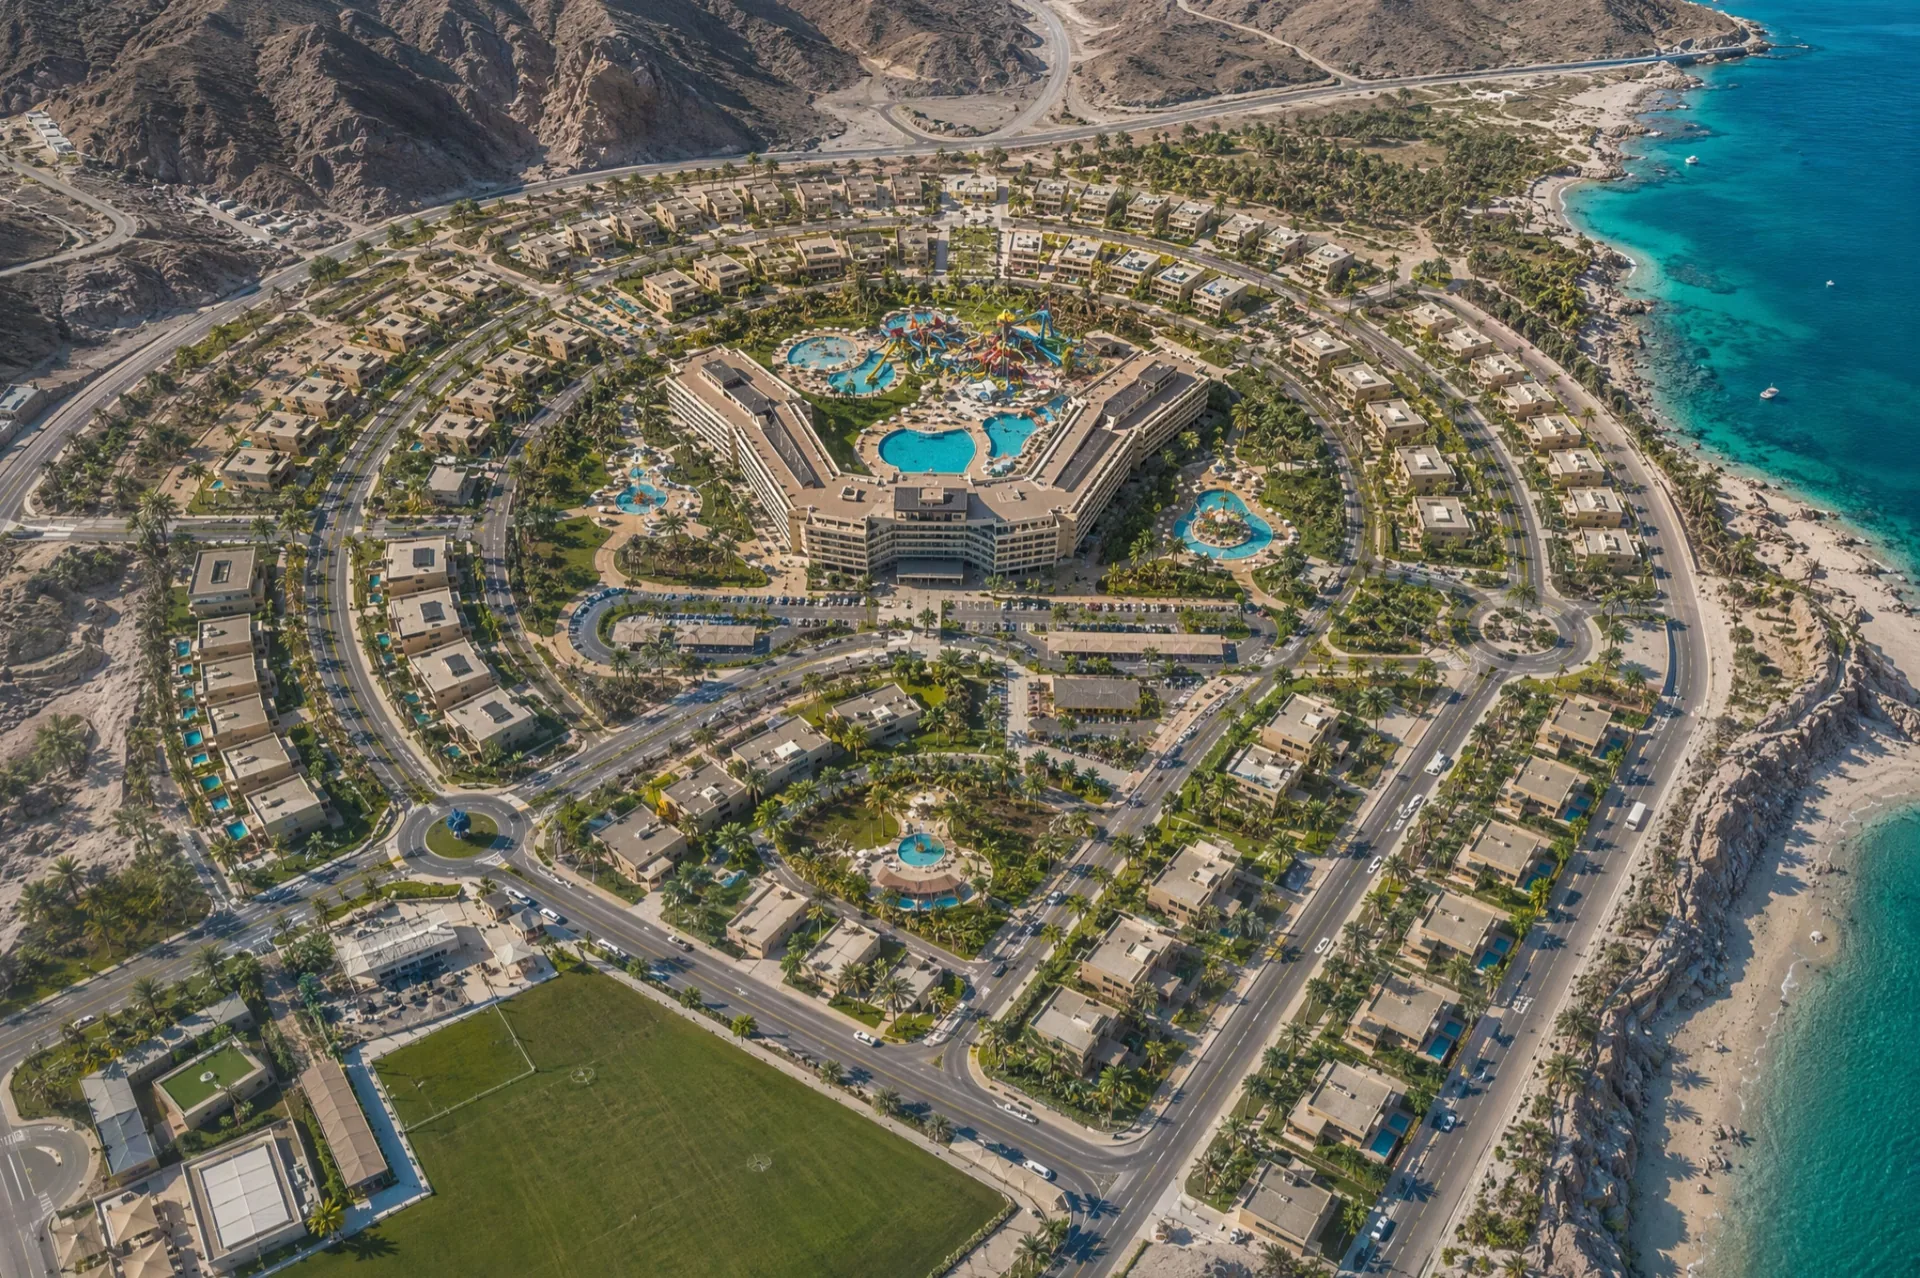
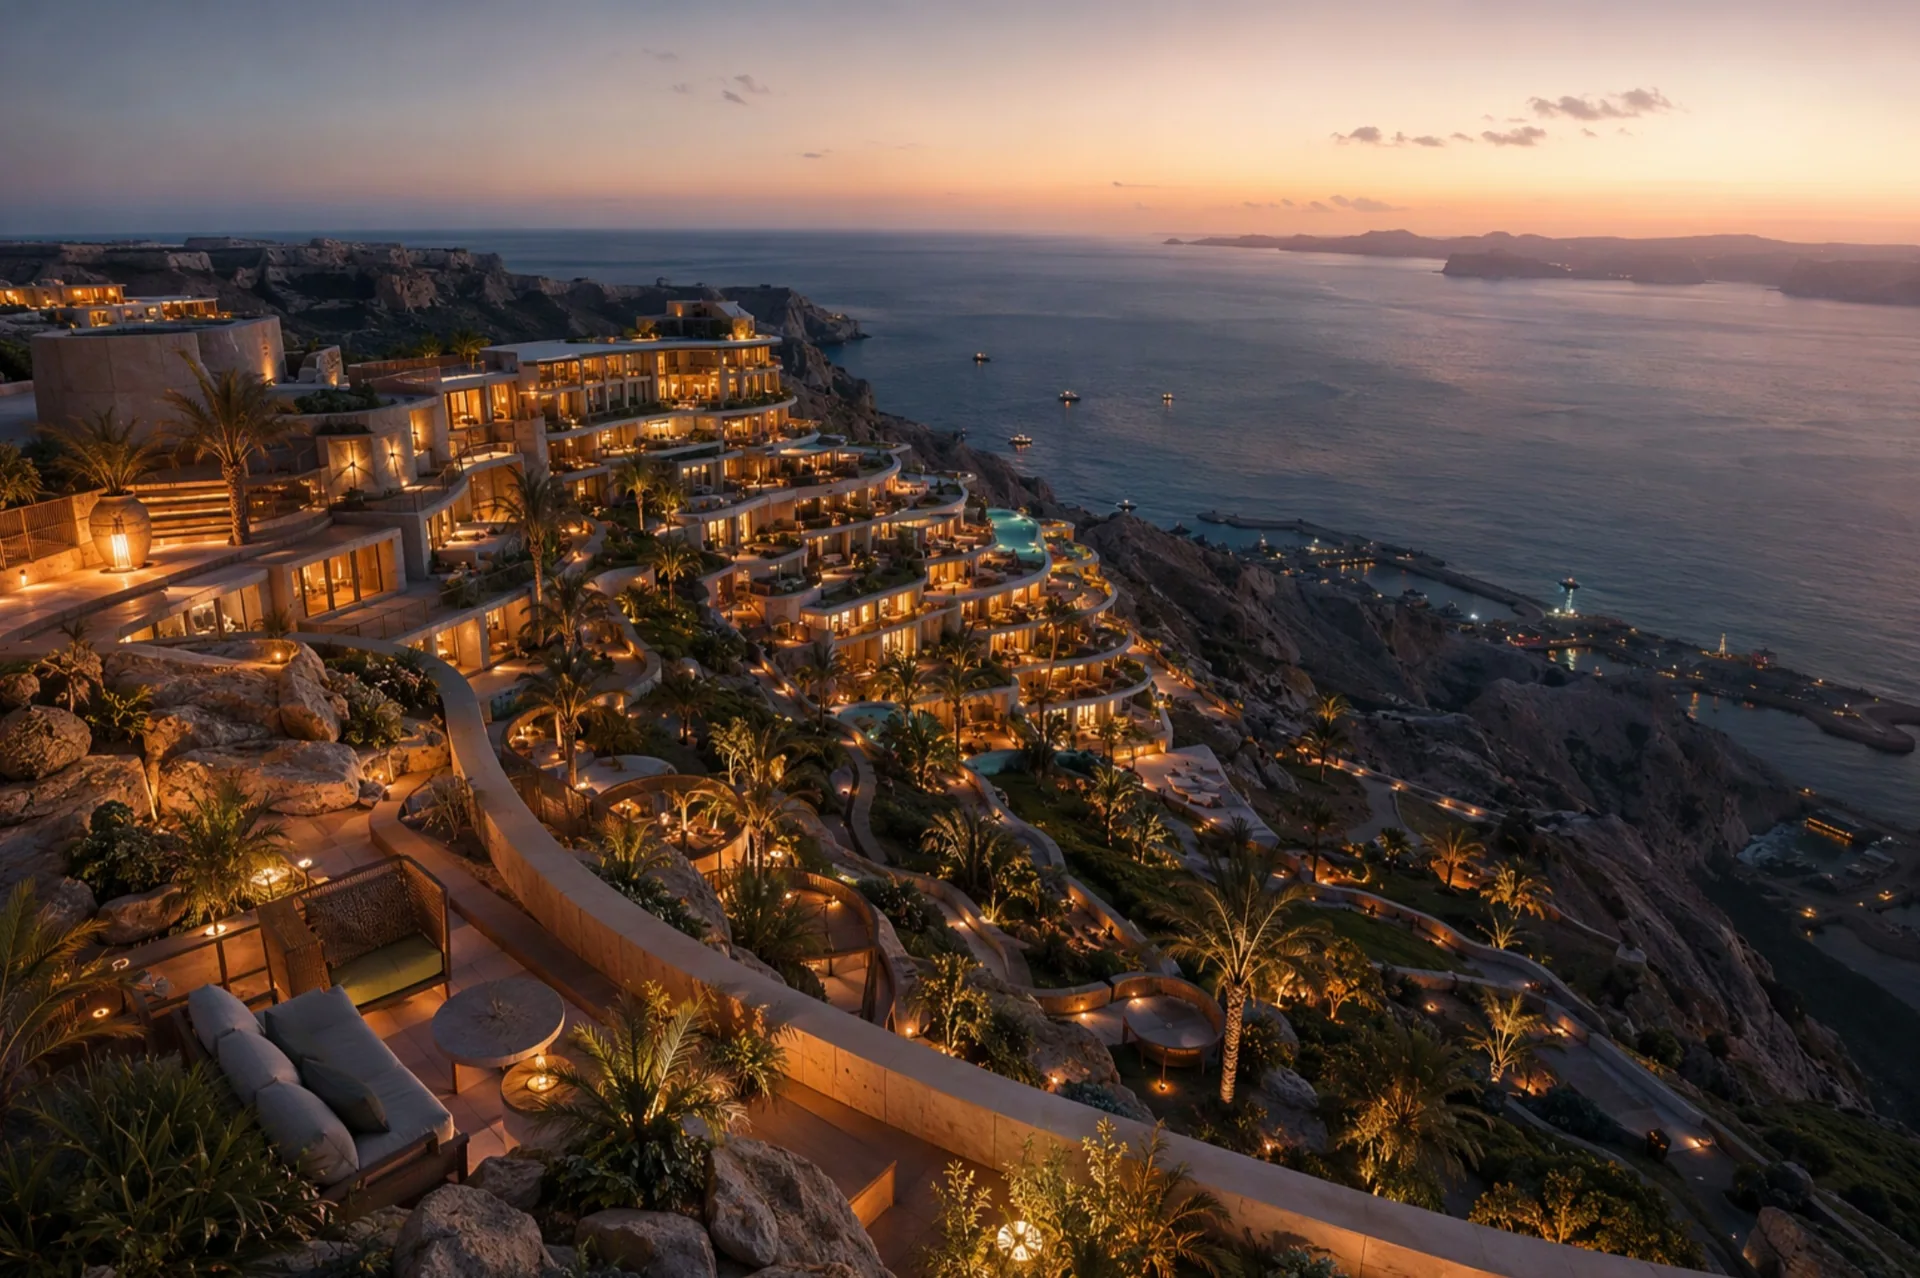
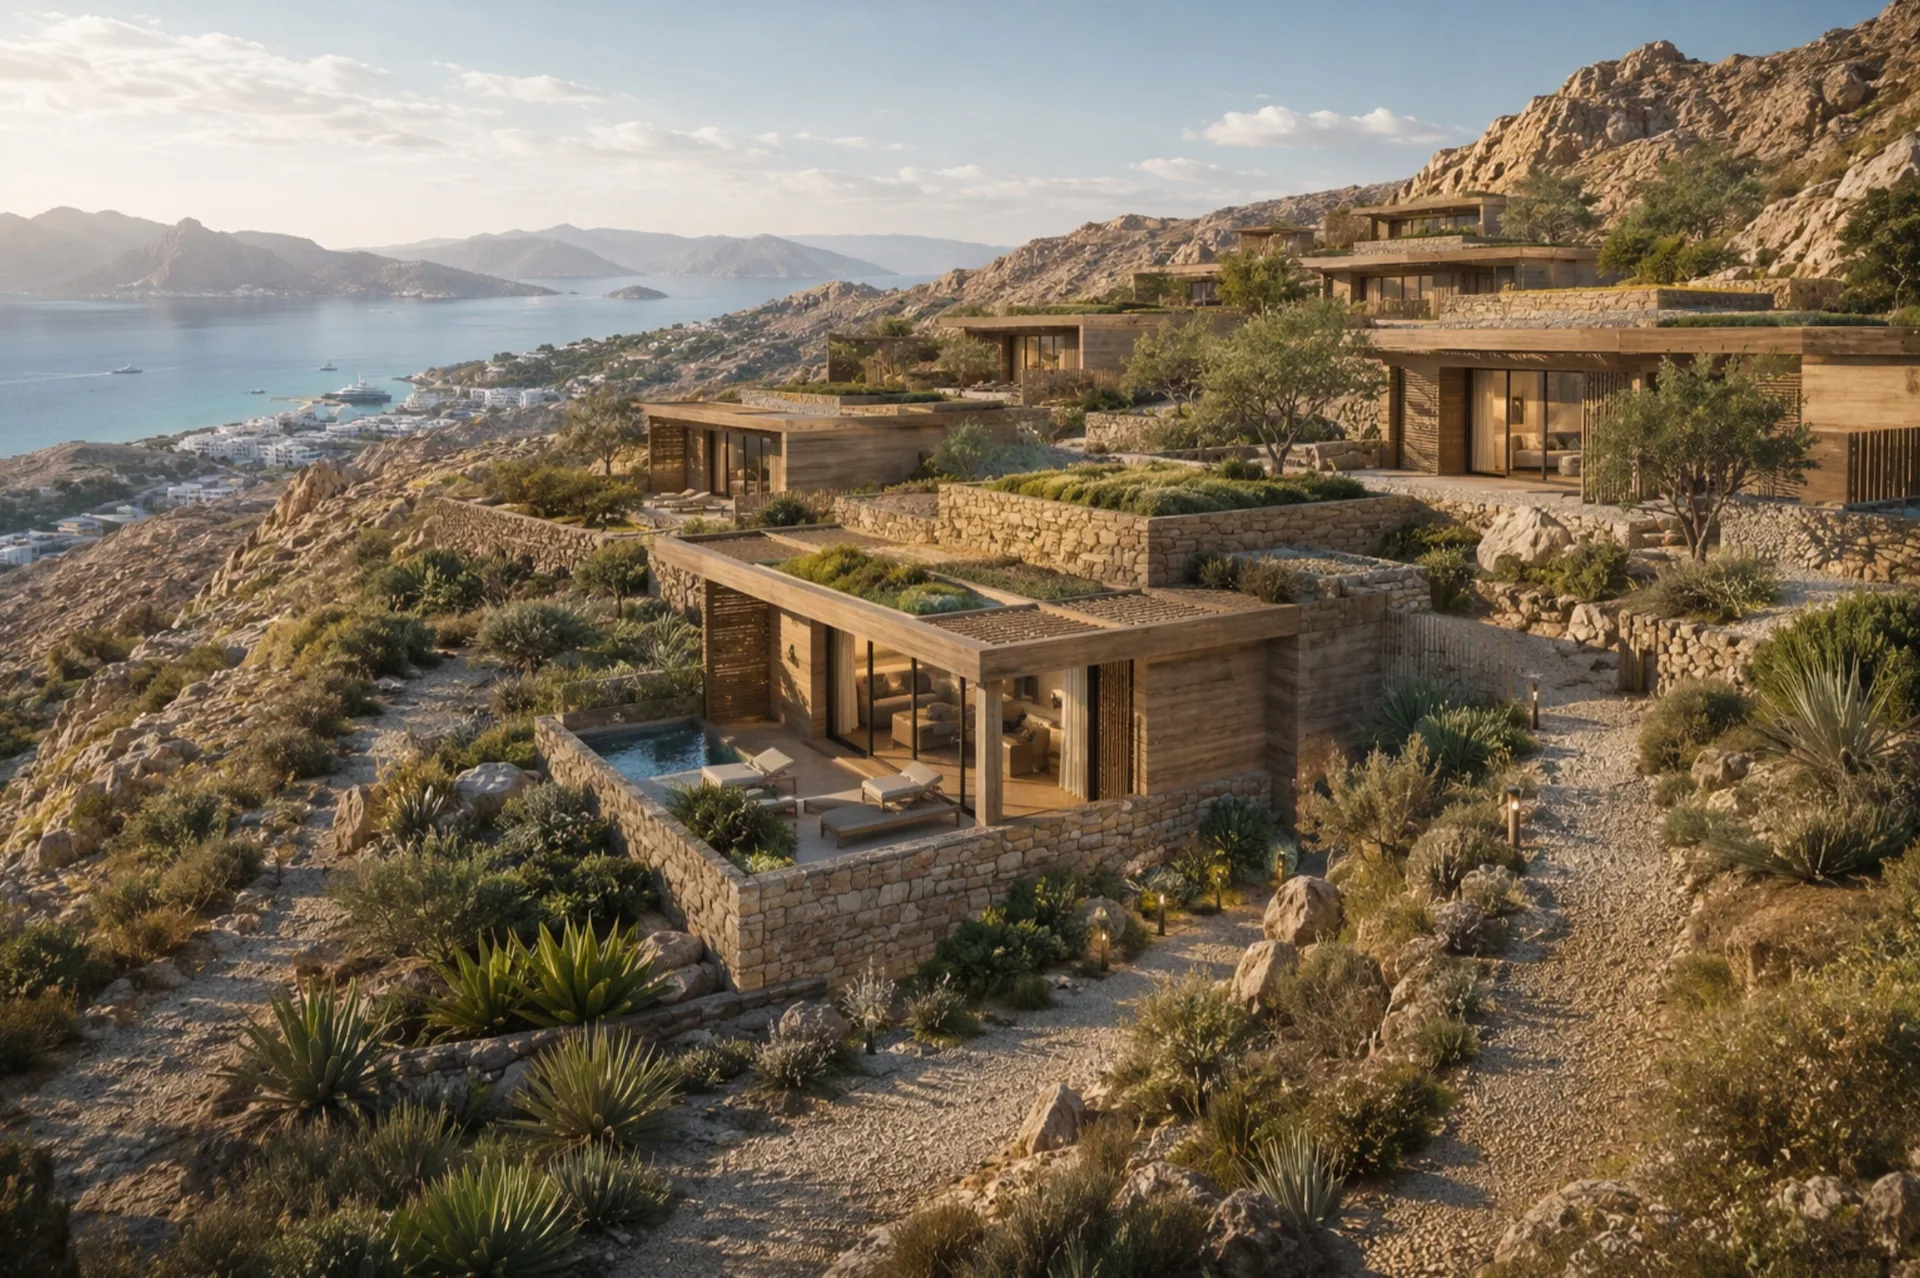
The master plan organises the site in concentric terraces around the summit: hotel and luxury villas claim the best sea-view crown; standard and eco villas step down the slopes; family leisure (aqua park, phase 2) sits on the flat southern land. The layout follows contour lines, preserves drainage channels, and separates pedestrian and vehicle flows. A note on vocabulary: the 2020 plan calls the units "chalets" by architectural typology; legally and commercially they are freehold ITC villas — 150–300 m² facing the sea, the same product nature sold to foreigners at Al Mouj, AIDA or Hawana.
| Component | Units / size | Position in plan |
|---|---|---|
| Crown hotel (phase 1) | 120 keys (est.) | Summit crown, best sea view |
| Luxury villas — 300 m² each (phase 1) | 30 | Summit ring +145/+150 m, sea-facing |
| Standard villas — 150 m² (phase 2) | 28 | Stepped terraces +130/+140 m |
| Eco villas — 150 m² (phase 2) | 21 | Stepped terraces, eco materials |
| Fine-dining restaurant (phase 1) | 186 m² | Scenic point |
| Wellness centre & spa (phase 1) | 400 m² | Therapeutic gardens |
| Aqua park & family leisure (phase 2, self-funded) | — | Flat southern land — triggered by proven occupancy |
| Land bank: 250+ keys & marina (phase 3) | — | Separately budgeted reserve, outside the model |


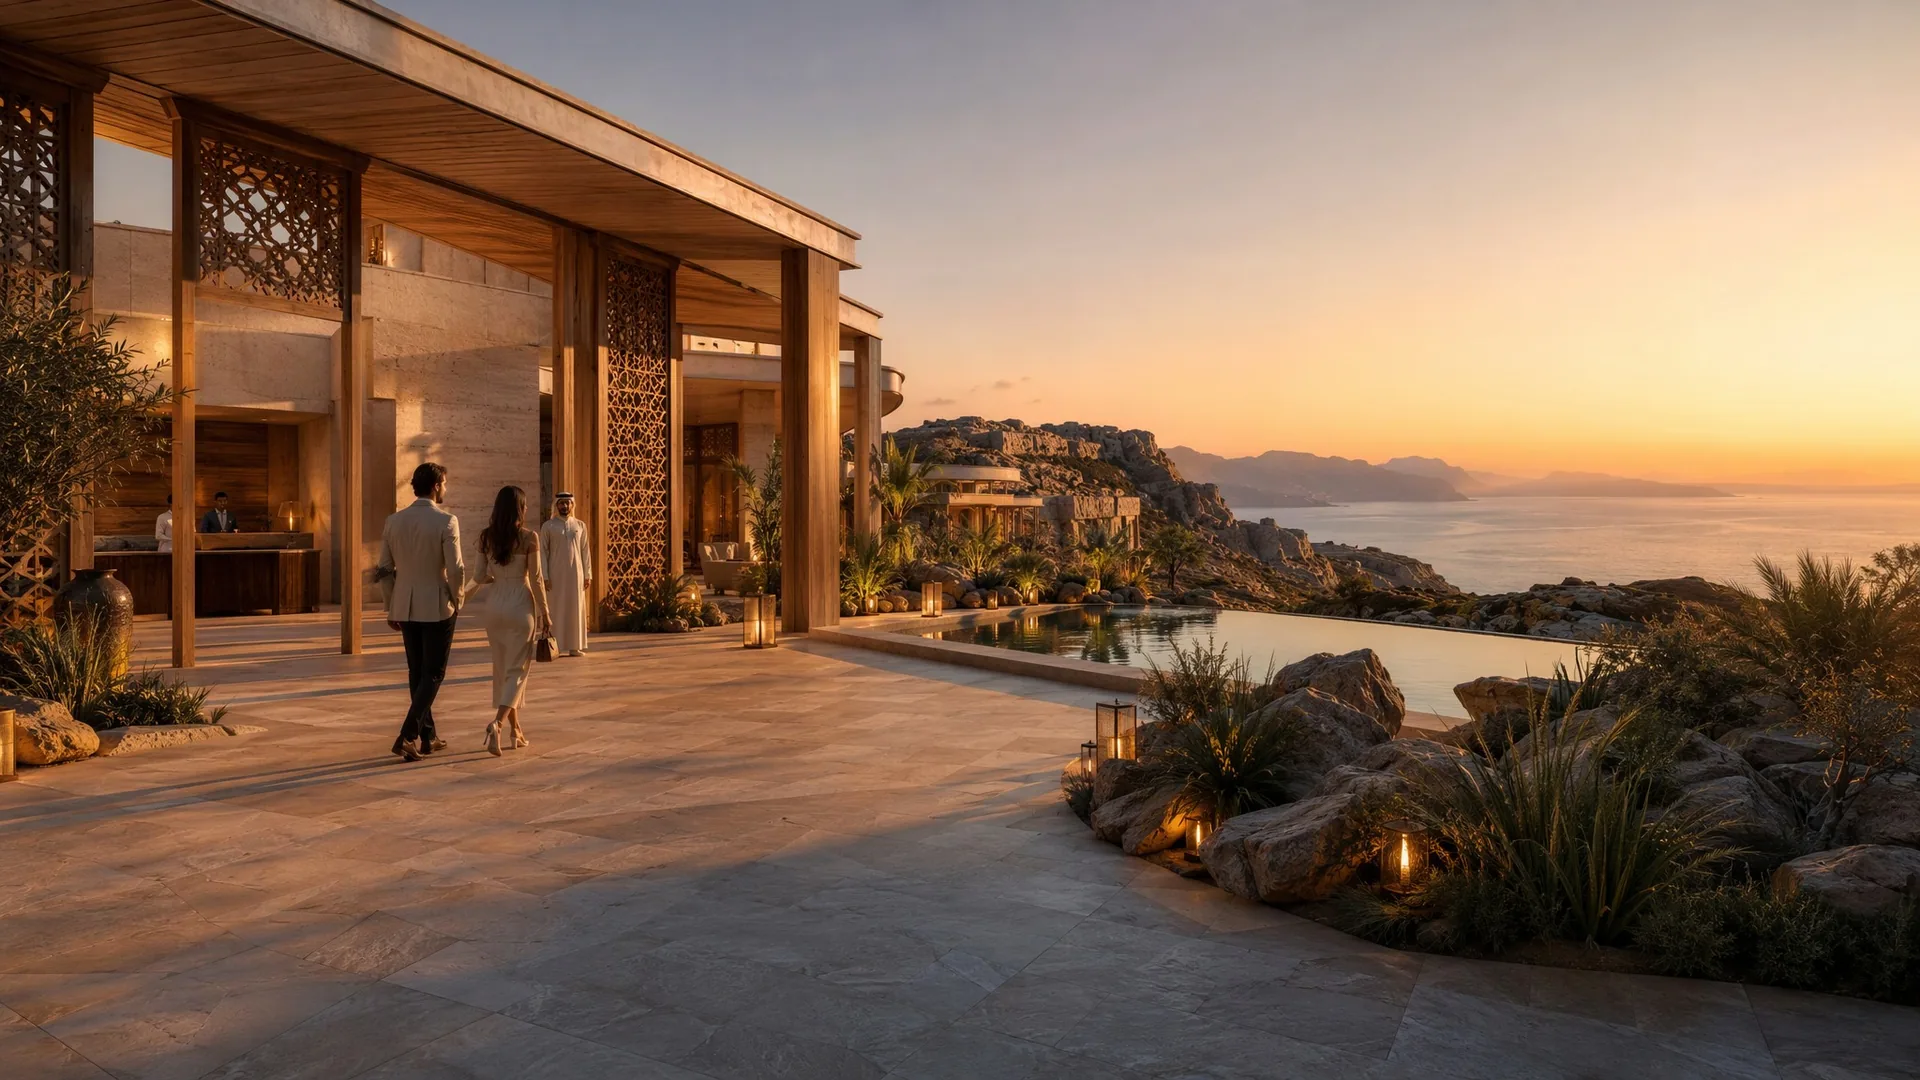
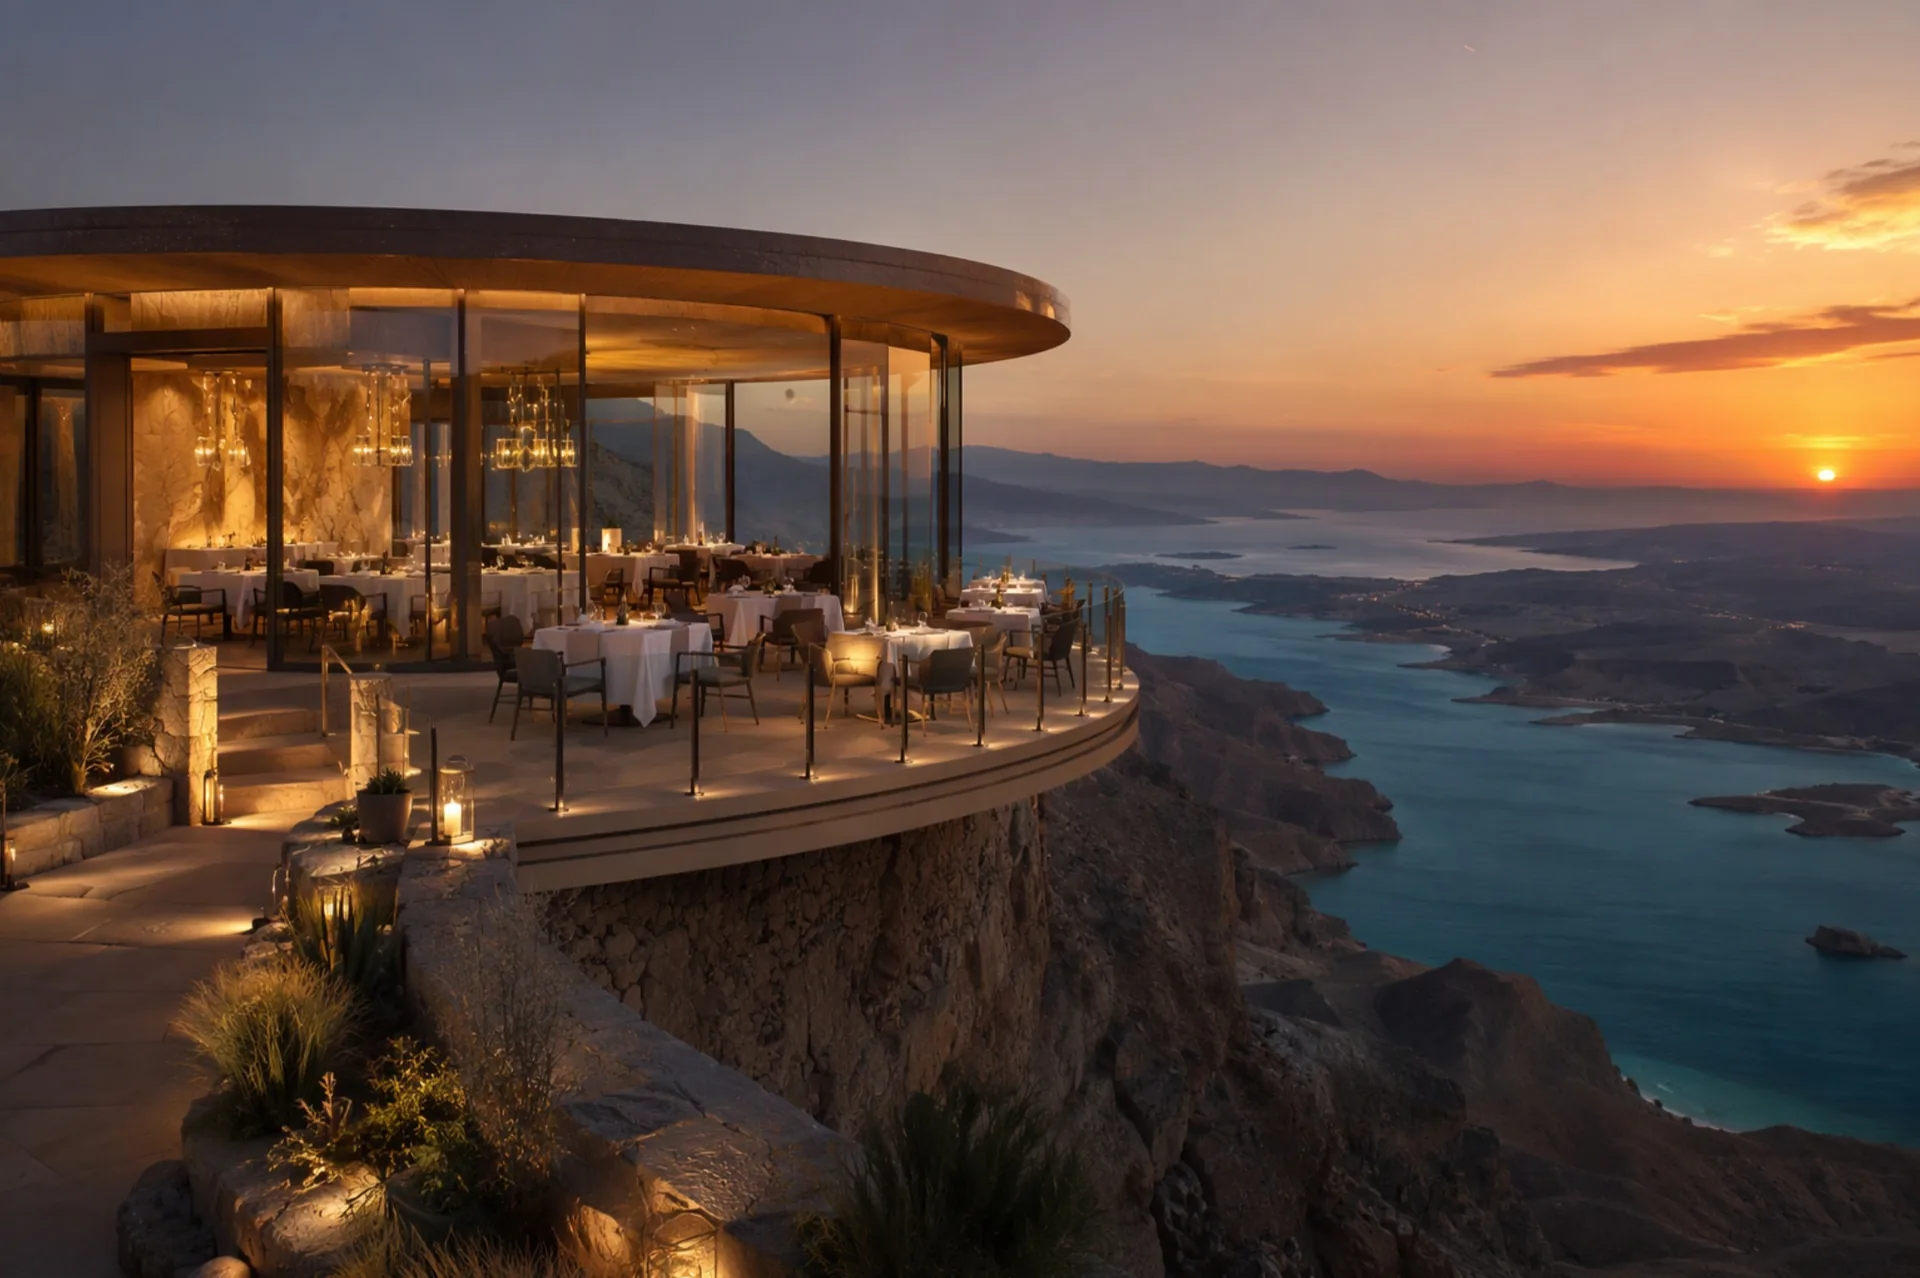
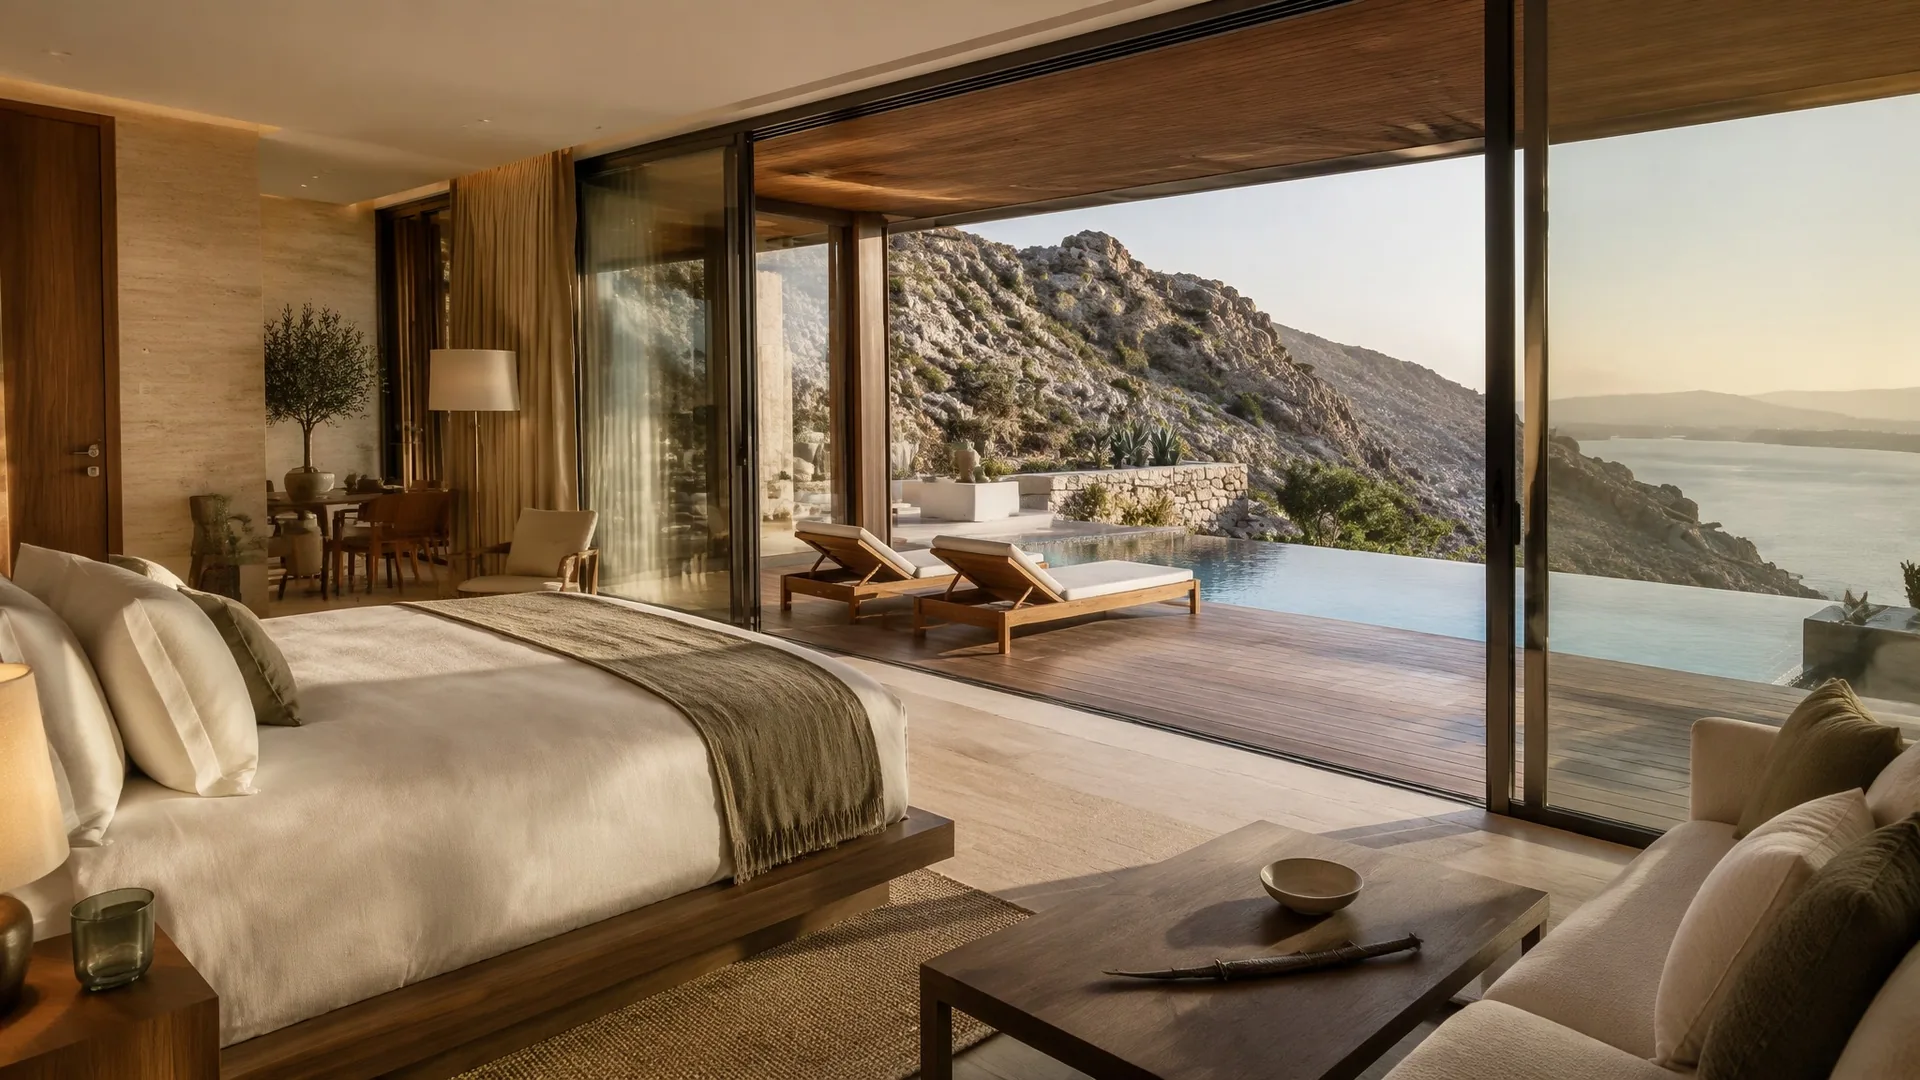
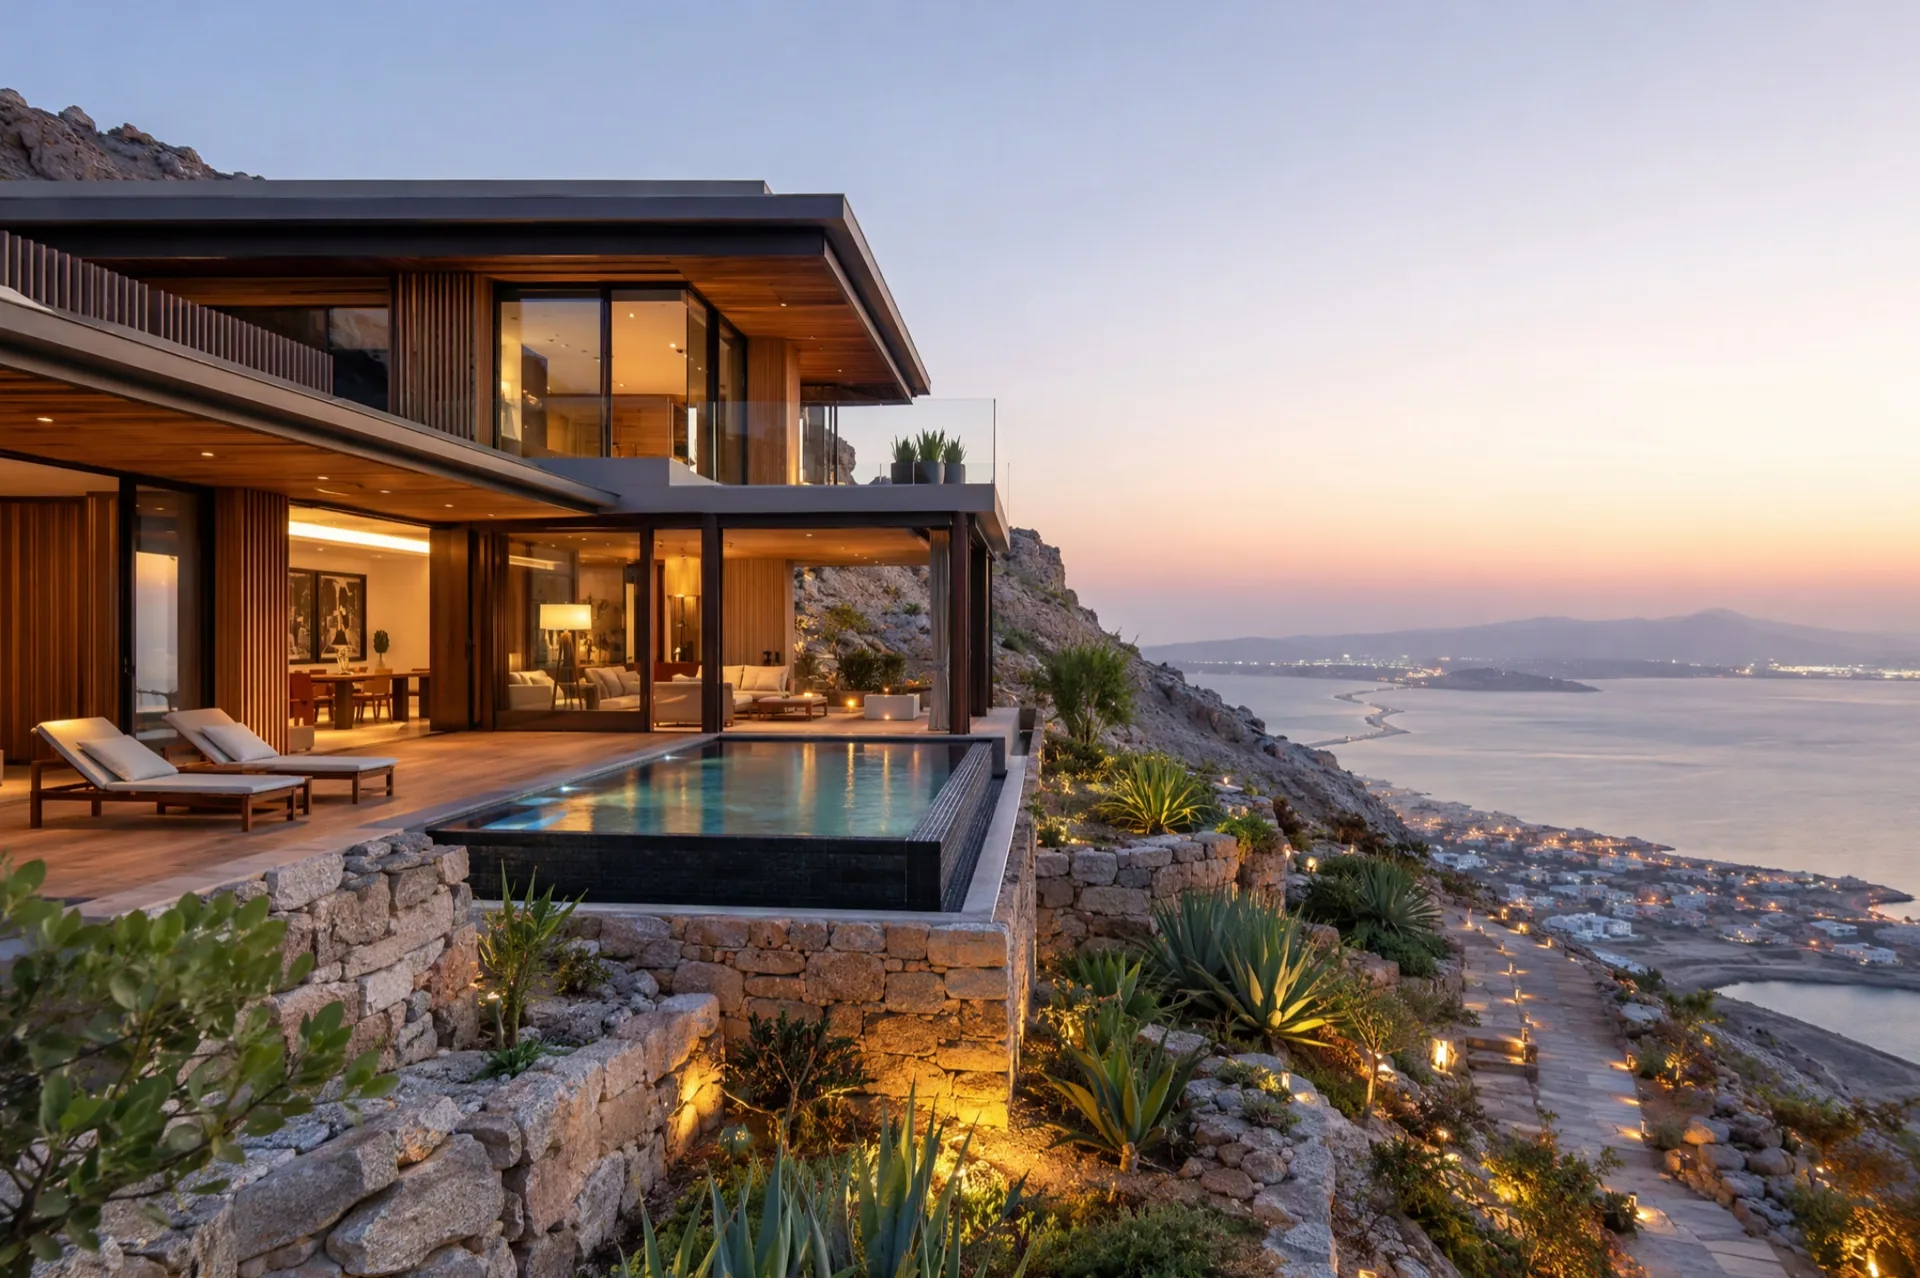
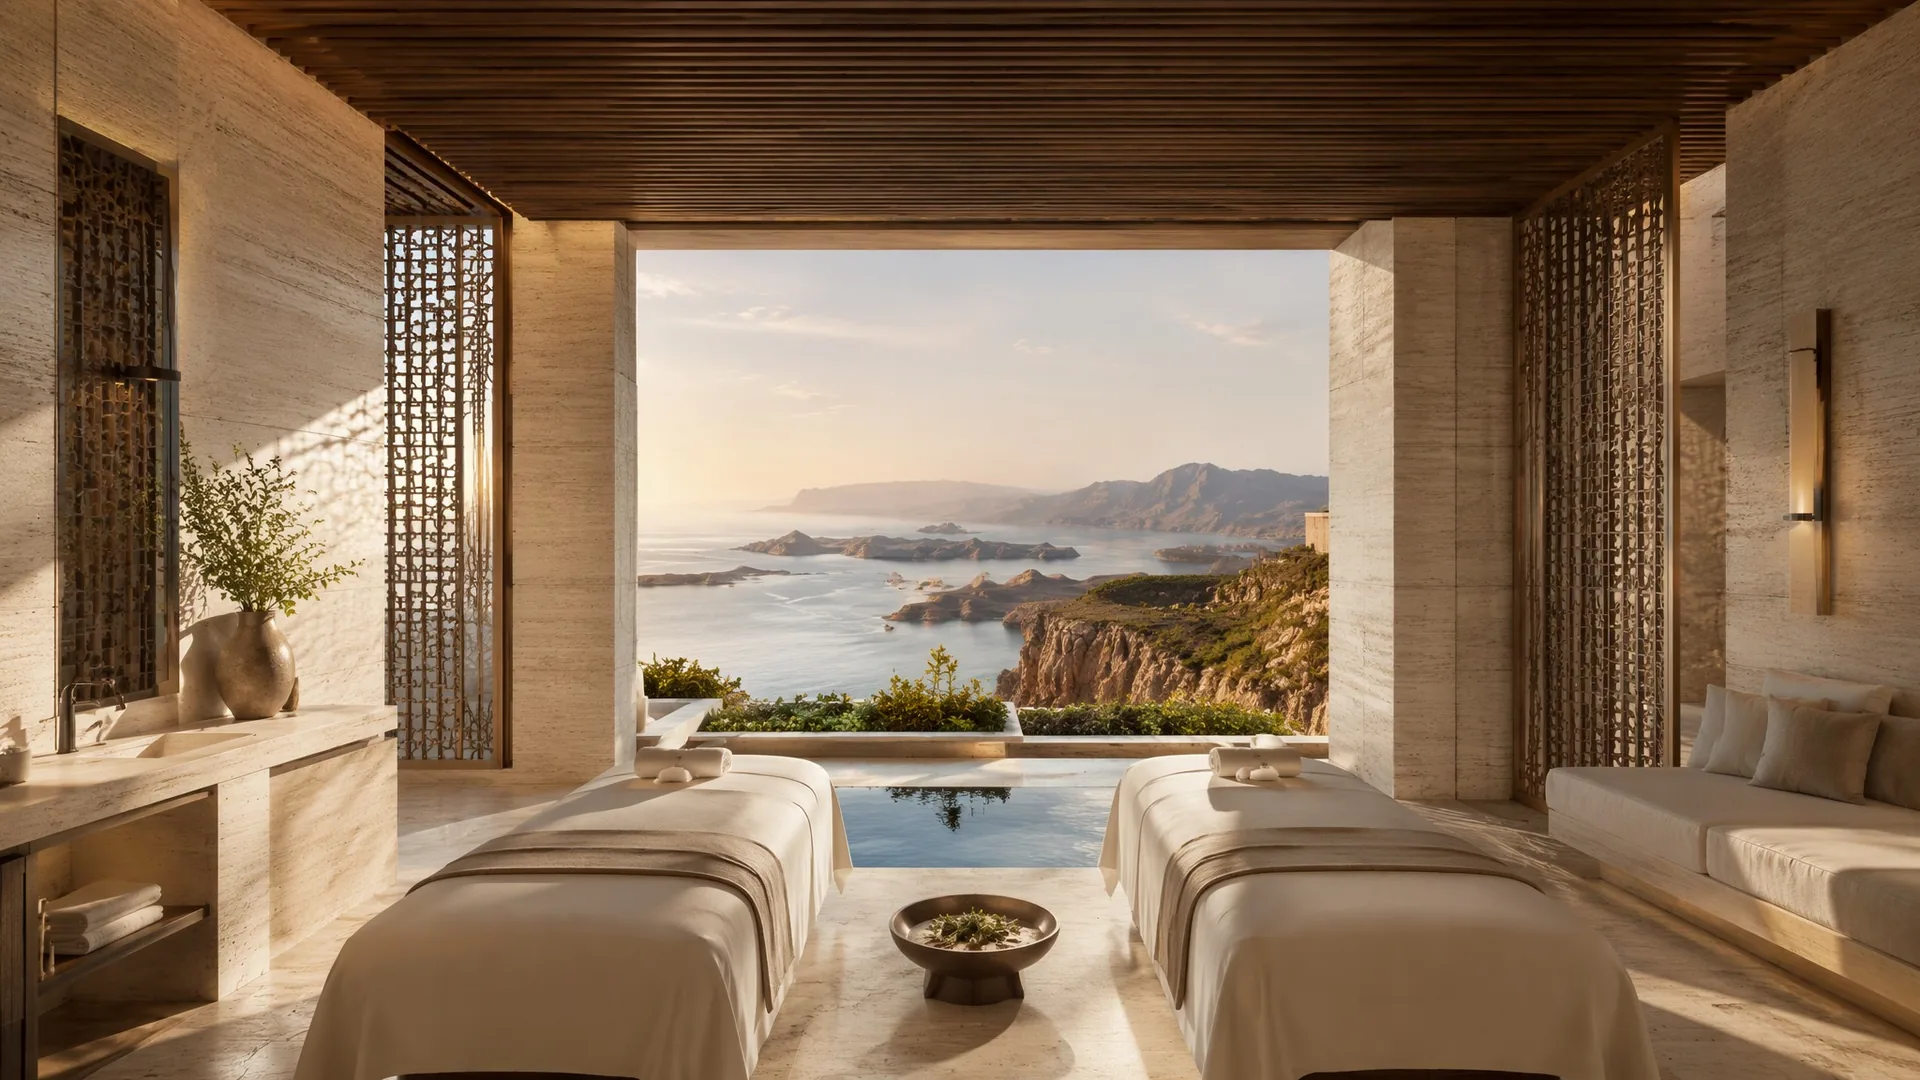
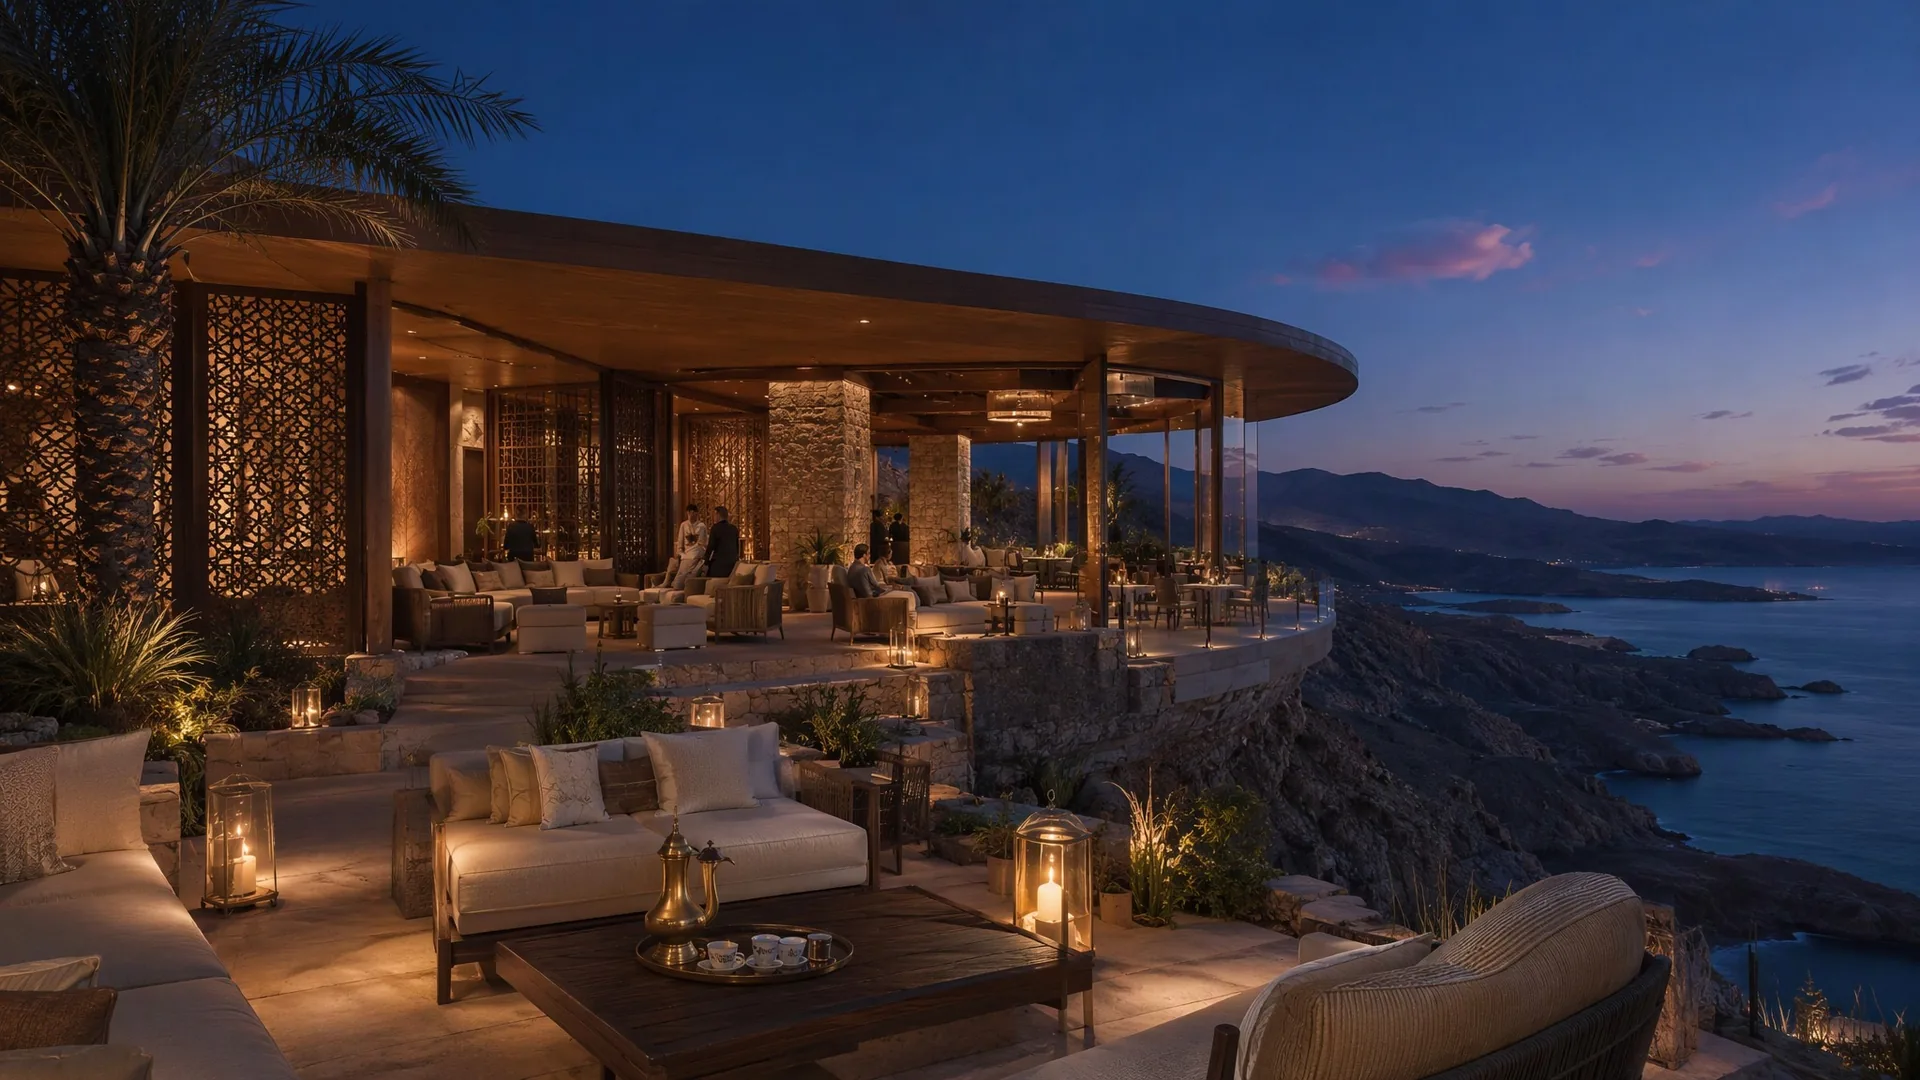
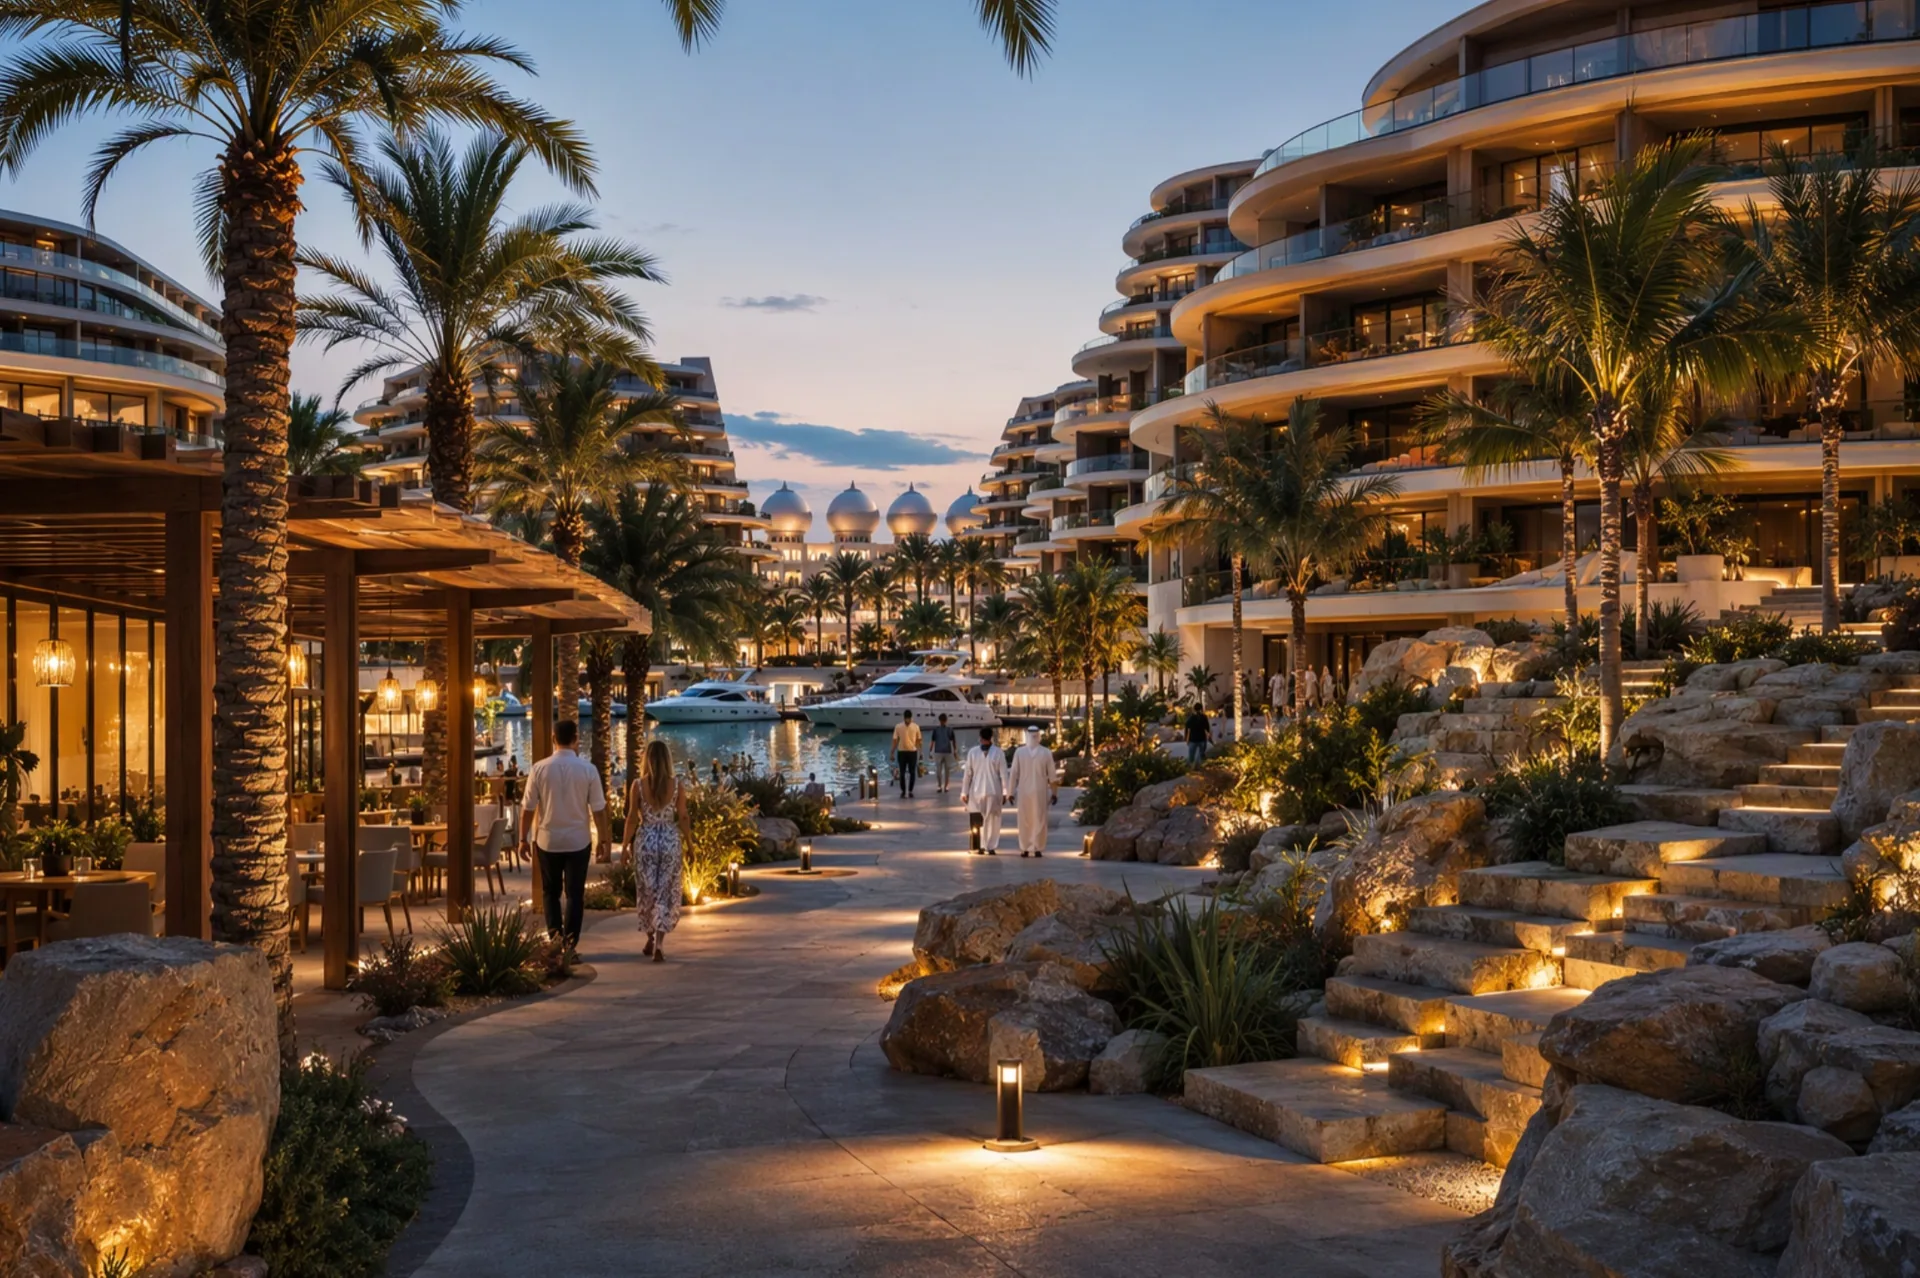
High-definition architectural perspectives of the project concept — summit hotel crown, terraced villas, wellness and dining above the sea.


“Demand is real, rated and growing — 2026 is a cycle, not a trend.”
Oman closed 2025 at 3.97 million visitors with hotel revenues of OMR 297.3 million (+22.2%) and market occupancy of 56.7%. H1 2026 softened to 46.3% on new supply — a classic absorption cycle inside a market the IMF sees growing 3.5% in 2026, with Muscat airport at 13.16 million passengers. Meanwhile, not one integrated resort operates within an hour of the airport.
2026 opens softer — H1 occupancy 46.3%, nine-month hotel revenues −11.7% — as fresh keys are absorbed. The structural drivers are intact: record 2025 demand, airport traffic at 13.16 M passengers and rising, IMF growth of 3.5%, and Vision 2040 tourism investment. We underwrite the resort at 48% occupancy in year one — below the 2025 market average of 56.7%.
| Project | Keys | Status | Read |
|---|---|---|---|
| Anantara Bandar Al Khairan — next to our site | 121 | Opening 2027 (official) | Demand catalyst; luxury tariff address |
| W Muscat (Marriott) | 279 | Operating since 2019 | OMR 32.7 M bank financing precedent |
| JW Marriott Muscat | 304 | Under construction | USD 98.7 M QNB facility — banks lend here |
| Jumeirah Muscat Bay · St Regis Al Mouj | 206 · 250 | Operating (2022 / 2024) | Luxury supply grows — none integrated, none in Bandar Al Khairan |
| Integrated resort < 1 h from Muscat airport | — | None | This site is the only candidate |
| Resort | Typical rate | Position |
|---|---|---|
| Al Husn (Shangri-La) | USD 624 | Top of market |
| Al Bustan Palace (Ritz-Carlton) | ≈ USD 412 | Grand heritage resort |
| St Regis Al Mouj | USD 384 | New luxury, marina district |
| The Chedi Muscat | OMR 150 ≈ USD 390 | Design icon, 21-acre gardens |
| Shangri-La Barr Al Jissah | ≈ USD 285 | Family resort anchor |
| Jumeirah Muscat Bay | ≈ USD 221 | Newest bay resort |
Achieved online rates, standard rooms — the resort's planned OMR 75–185 (USD 195–480) band sits inside the proven range. Sources §14.
High-altitude sea-view resort with private-cove access, villas plus hotel plus spa under one operator, self-contained utilities — aligned with Vision 2040 and the MHT's USD 31 billion tourism pipeline. Nothing comparable exists within an hour of the airport; Anantara's 2027 opening validates the bay before our first guest arrives.
| Item | Regime | In the model? |
|---|---|---|
| Corporate income tax | 15% | Yes — fully applied |
| VAT | 5% | Yes — fully applied |
| Tourism tax 4% · municipal 5% · land registration 3% | 3–5% | Yes — fully applied |
| Tax holidays 5–15 years (tourism projects) | 0% possible | No — upside not counted |
| Customs exemptions on hotel equipment | Case-by-case | No — upside not counted |
| MHT marketing support · Vision 2040 alignment | — | No — upside not counted |
Incentives are excluded from the financial model: every riyal of incentive improves the published returns. AHK / PwC / royal decrees — sources §14.
Land rights, development permits, tourist classification and ITC status are subject to legal and administrative verification. Authorisations obtained are distinguished from ongoing procedures and from validations still required.
| Item | Status | Evidence / milestone |
|---|---|---|
| Land title — 113,477 m² parcel, registered in the promoter's name | Confirmed | Title deed & site surveys, 2023 (DIM-02) |
| Land-use re-designation to Integrated Tourism Complex (ITC) | In progress | File with MHT / MHUP since 2023 — milestone Q1 2027; no construction draw before designation |
| Environmental impact assessment (EIA) | In progress | Milestone H1 2027, before any capital draw |
| Tourist classification of the hotel | To be validated | Filed after detailed design; 4★+/5★ positioning targeted |
| Operator letter of intent (LOI) | To be validated | Target H1 2027 — a phase-0 gate |
| Bank financing — the 60/40 structure is envisaged, not committed | To be validated | Indicative terms only; financing close is a 2027 gate |
Sources: title register DIM-02 and 2026 model (DIM-03) — full register in §14.
Phase 1 costs OMR 16.4 million, drawn 2027–2029 and financed 60/40 (debt OMR 9.84 M at 5.5% over 20 years, equity OMR 6.56 M). On opening in 2030 the resort ramps 48% → 65% occupancy at a blended ADR (average daily rate) of OMR 74.7 (~USD 194), reaching OMR 4.82 M revenue and a 40.5% EBITDA margin by 2033. Villa sales of OMR 12.6 M deleverage the structure to OMR 0.84 M residual debt by 2032.
Methodology: cash flows 2027–2039, year-10 exit, three scenarios (downside / central / favourable) from the 2026 model (DIM-03). Projected figures — no return is guaranteed. Hotel operating flows, villa sales and investor distributions are separate flows; distributions only once DSCR ≥ 1.4×.
| Year | Keys | Occupancy | Revenue | EBITDA | Margin |
|---|---|---|---|---|---|
| 2030 | 150 | 48% | 3.56 | 1.44 | 40.5% |
| 2031 | 150 | 55% | 4.08 | 1.65 | 40.5% |
| 2032 | 150 | 62% | 4.59 | 1.86 | 40.5% |
| 2033 | 150 | 65% | 4.82 | 1.95 | 40.5% |
Blended ADR OMR 74.7 (~USD 194); net cash flow to shareholders OMR 1.13 M → 1.62 M; DSCR 2.37×; break-even ≈ 30–32% occupancy (≈ ADR OMR 55).
| Scenario | Project IRR | vs 11.3% base |
|---|---|---|
| Capex −10% | 12.9% | +1.6 pt |
| ADR +10% | 12.7% | +1.4 pt |
| Occupancy −5 pts | 10.2% | −1.1 pt |
| Capex +10% | 10.0% | −1.3 pt |
| ADR −10% | 9.9% | −1.4 pt |
| EBITDA margin −5 pts | 9.5% | −1.8 pt |
| Catastrophe: capex +15%, ADR −15%, occupancy −10 pts, margin −8 pts | ≈ 5–6% | DSCR ≈ 1.6× · exit OMR 15.8 M at a 9.0% cap — capital preserved |
No single plausible stress pushes the project below its 10% floor except the margin shock; the combined catastrophe case still preserves capital. Model: cash flows 2027–2039, exit at year-10.
“Three moves: secure the land, build the core, let the land bank pay for the rest.”
The 2020 concept failed because it tried to build everything at once, on an unsecured title, without an operator. This plan inverts that: three sequenced moves, each unlocked by a milestone, each fundable on its own.
Land designation change to ITC (Q1 2027), EIA approval and operator LOI (H1 2027), financing close (2027). Capital at risk before these gates: studies and fees only.
120-key hotel, 30 luxury villas, restaurant and spa — OMR 16.4 M drawn 5.74 / 7.38 / 3.28 across 2027–2029. Opening 2030, the year after Anantara has established the bay.
Sell 79 villas for OMR 12.6 M (30/45/25% across 2030–2032), deleverage to OMR 0.84 M residual debt, then decide phase 3 — a 250+ key land bank and marina option — from strength.
| Phase | Window | Deliverables | Gate to proceed |
|---|---|---|---|
| 0 — Securing | 2027 | ITC designation, EIA, operator LOI, financing close | All four confirmed — else no construction capital is drawn |
| 1 — Construction | 2027–2029 | Hotel 120 keys, 30 luxury villas, F&B 186 m², spa 400 m², utilities | Certified milestones, escrowed draws, independent audit |
| 2 — Opening & sales | 2030–2032 | Opening 2030; villa sales OMR 12.6 M; occupancy 48→62% | Sales velocity ≥ plan before phase-2 villa construction completes |
| 3 — Expansion option | 2033+ | Land bank 250+ keys, marina option (separate SPV) | Funded from retained cash + asset value, not new equity |
The 2020 study proposed a single-phase mega-build with no operator, no ITC designation and no demand catalyst nearby. This plan builds only what the market absorbs first, enters after Anantara has validated the bay, and keeps phase 3 as an option rather than a promise.
| Exit cap rate | Asset value | vs cost |
|---|---|---|
| 8.5% (conservative) | OMR 22.9 M | +40% |
| 8.0% (base) | OMR 24.4 M | +49% |
| 7.5% (prime) | OMR 26.0 M | +59% |
Oman resort transactions clear at 7.5–8.5% caps; a stabilised, branded, ITC-titled resort with a land bank argues for the base case or better. Catastrophe case: OMR 15.8 M at 9.0% — still ≈ cost.
| Product | Price | Benchmark |
|---|---|---|
| 30 luxury villas (Phase 1) | OMR 250,000 | St Regis Al Mouj branded residences from OMR 339,000 |
| 28 standard villas (Phase 2) | OMR 110,000 | AIDA/Yiti villas OMR 112,000–385,000+ |
| 21 eco villas (Phase 2) | OMR 95,000 | Hawana Salalah entry product from OMR 98,000 |
Every unit qualifies its buyer for the 10-year Golden Residency (threshold OMR 200,000 met via unit + share of common assets, or directly for luxury villas). Total sales OMR 12.6 M; OMR 9.0 M applied to deleveraging.
| Instrument | Equity in a single-asset Omani SPV (LLC), 100% foreign-owned under FCIL |
| Phase-1 capital | OMR 16.4 M |
| Structure | 60% senior debt OMR 9.84 M (5.5%, 20 y) · 40% equity OMR 6.56 M |
| Equity returns | Projected IRR 15–17% (2026 model, incl. year-10 exit at the 8.0% base cap) · cash-on-cash 17.2% at stabilisation · projections, not a guaranteed return |
| Distribution policy | Annual distributions once DSCR ≥ 1.4×; sales proceeds to deleveraging first |
| Alignment | Promoter carry only above a 10% equity hurdle; veto rights for investors on budget, debt and phase-3 decisions |
| Exit routes | Asset sale to an operator/REIT, refinance + hold, or unit-by-unit villa sell-down |
Oman Arab Bank financed the W Muscat (OMR 32.7 M); QNB led a USD 98.7 M facility for the JW Marriott Muscat. Our OMR 9.84 M senior ask is small by comparison, at a conservative 60% LTC with a 2.37× DSCR.
| # | Protection | Mechanism |
|---|---|---|
| 1 | Escrowed draws | All construction payments against engineer-certified milestones; no advance payments |
| 2 | Independent audit | Big-4 or equivalent annual audit; quarterly investor reporting |
| 3 | Investor veto rights | Budget >5% variance, new debt, related-party contracts, phase-3 launch |
| 4 | Gated capital | Phase gates: no draw before ITC designation, EIA, operator LOI and financing close |
| 5 | Distribution lock-up | No distributions while DSCR < 1.4× or debt > 40% of asset value |
| 6 | Operator alignment | Operator fees partly performance-based; key-money or sliver equity targeted |
| 7 | Promoter hurdle | Carry only above a 10% equity IRR hurdle — investors are paid first |
The catastrophe scenario — capex +15%, ADR −15%, occupancy −10 pts, margin −8 pts — still returns an IRR of ≈ 5–6% with a DSCR of ≈ 1.6× and an exit value of OMR 15.8 M at a 9.0% cap. The structure is built so the worst realistic case preserves capital.
Because it starts below the market. Muscat hotels averaged 56.7% occupancy in a record 2025; we underwrite 48% in year one for a branded resort next to an operating Anantara, reaching 65% only in year four — in line with HVS ramp benchmarks for the Gulf.
Then construction capital is never drawn. The ITC designation is the first gate (Q1 2027): studies and fees are the only capital at risk until it, the EIA, the operator LOI and financing close are all confirmed.
A branded operator under a management agreement, with LOI targeted for H1 2027. Anantara's arrival proves international operators will commit to this bay; fee structures with performance components and key-money are being negotiated.
Three routes: sale of the stabilised asset to an operator, sovereign-backed fund or REIT at a 7.5–8.5% cap; refinance and hold with 17.2% cash-on-cash; or unit-by-unit villa sell-down (OMR 12.6 M of product at prices below comparable Omani resorts).
The Omani rial is pegged to the US dollar (1 OMR = 2.6008 USD) and FCIL guarantees free transfer of capital and profits. There is no FX mismatch: rates are dollar-linked, debt is local.
Entry pricing. Investors entering before the 2027 gates fund at cost and capture the full development margin (+40–59% to exit value); after 2030 they would pay the stabilised valuation. The gates exist precisely so early capital is protected while it earns that margin.
Completion of the investment may be conditioned on the following validations. The protections described in §11 become effective only once contractualised.
| 1 | Validation of land rights and ITC designation |
| 2 | Clarification of the regulatory framework (EIA, tourist classification, building permits) |
| 3 | Confirmation of budget and financing (capex, contingencies, debt terms) |
| 4 | Independent review of the financial model |
| 5 | Signature of the legal and governance documentation of the SPV (escrow, veto rights, reporting) |
| Risk | Level | Mitigation in the plan |
|---|---|---|
| Land designation change delayed beyond Q1 2027 | High | Hard gate: no construction draw before designation; process running since 2023 with MHT/MHUP; clean title already in promoter's name |
| EIA conditions add cost or delay | Medium | OMR 0.7 M contingency; low-density masterplan; cove access designed around marine protection; H1 2027 milestone before capital draws |
| Operator terms below assumption | Medium | LOI is a phase-0 gate; multiple operators active in Muscat (Marriott, Jumeirah, IHG, Minor); performance-fee structure preserves margin |
| 2026 demand softness extends | Medium | Opening is 2030 — after the absorption cycle; underwriting starts at 48% occupancy vs 56.7% market average in 2025 |
| Construction cost inflation | Medium | T&T Gulf cost benchmarks; +10% capex stress still yields 10.0% IRR; fixed-price EPC targeted at financing close |
| Villa sales slower than 30/45/25% | Medium | Prices set below Hawana/AIDA/St Regis benchmarks; Golden Residency eligibility; deleveraging timeline flexes without covenant breach (DSCR 2.37×) |
| Financing terms worse than 5.5% / 20 y | Medium | Local precedents (W Muscat, JW Marriott) at larger sizes; 60% LTC; sovereign BBB−/Baa3 backdrop supports pricing |
| Competition from new luxury supply | Low | No integrated resort within 1 h of the airport; Anantara is a demand catalyst, not a substitute (121 keys vs 150+79 villas + spa + dive) |
| Exit cap-rate widening | Low | Base exit at 8.0% within the observed 7.5–8.5% Oman range; catastrophe case at 9.0% still ≈ preserves capital |
| Key-person dependency on promoter | Low | SPV governance, independent audit, veto rights, professional management from phase 0 |
Internal project documents (DIM register) and public sources, dated. Where a figure is an assumption, the model says so; everything else traces to the register below.
| Ref | Document | Date | Used for |
|---|---|---|---|
| DIM-01 | AlKhyran Heights feasibility study (original concept) | 2020 | Site data, masterplan basis, original program |
| DIM-02 | Land title and site surveys, Bandar Al Khairan parcel | 2023 | Ownership, boundaries, topography, 150 m elevation |
| DIM-03 | Updated financial model (this study) | 2026 | IRR, NPV, ramp, sensitivity, capex, structure |
| DIM-04 | 3D concept model and visualisations | 2026 | Masterplan plate, perspective renders, 3D model (generated with Tripo) |
| Source | Type | Used for |
|---|---|---|
| IMF Article IV / WEO — Oman | Macro | Growth 3.5% (2026), debt ≈ 36% of GDP |
| Fitch (Dec 2025) · Moody's (Jul 2025) · S&P (Sep 2024) | Macro | Sovereign ratings BBB− / Baa3 / BBB−, stable outlooks |
| NCSI — Oman hotel & tourism statistics | Market | 3.97 M visitors, occupancy 56.7% (2025) / 46.3% (H1 2026), revenue OMR 297.3 M, 9M 2026 −11.7% |
| Muscat International Airport (OACI/Oman Airports) | Market | 13.16 M passengers (2025, +12.6%) |
| Cavendish Maxwell · Savills · Knight Frank — Oman market reports | Market | Residential/villa benchmarks (AIDA, Yiti, Al Mouj), cap-rate range 7.5–8.5% |
| HVS — Muscat hospitality & GCC operator fee surveys (×2) | Market | Occupancy ramp conventions, operator fee structures |
| Turner & Townsend — Gulf construction cost benchmarks | Cost | Capex per key, infrastructure cost checks |
| Minor Hotels / Anantara announcement · Oman Observer | Market | Anantara Bandar Al Khairan: 121 keys, OMR 36 M, opening 2027 |
| MHT — Ministry of Heritage & Tourism | Policy | Vision 2040 tourism pipeline (USD 31 bn), ITC program, incentives |
| AACO / airline schedules | Market | Air connectivity trends |
| Royal Decrees 50/2019 (FCIL) · 12/2006 (ITC) · ROP 87/2026 (Golden Residency) | Legal | Foreign ownership, freehold in ITCs, 10-year residency from OMR 200,000 |
| AHK · PwC Oman tax summaries | Legal | CIT 15%, VAT 5%, tourism/municipal taxes, registration 3% |
| Bank disclosures — Oman Arab Bank (W Muscat) · QNB (JW Marriott) | Finance | OMR 32.7 M and USD 98.7 M hospitality financing precedents |
| Developer listings — Hawana Salalah, AIDA, St Regis Al Mouj | Market | Villa price benchmarks OMR 98k / 112k / 339k |
| Achieved-rate checks — Chedi, Al Bustan, Al Husn, Jumeirah, Shangri-La, St Regis | Market | Luxury ADR range USD 221–624 (2025–2026) |
The full financial model (Excel), the DIM document register, legal opinions on FCIL/ITC structuring and the 3D model files are available in the data room under NDA. Site visits are organised monthly from Muscat — 45 minutes from the airport, the last 10 by boat if the sea is calm.
Model, DIM-01–04 register, source register with live links, draft SPV term sheet.
Guided visit of the 113,477 m² parcel, the cove and the Anantara site next door.
Gates close Q1–H1 2027; allocations are confirmed on a first-committed basis.
OMR 6.56 M equity sought · projected equity IRR 15–17% (2026 model) · gates 2027 · target opening 2030
Request the investor dossier